TD's deputy chief economist says markets are wrong about Bank of Canada mirroring the Fed
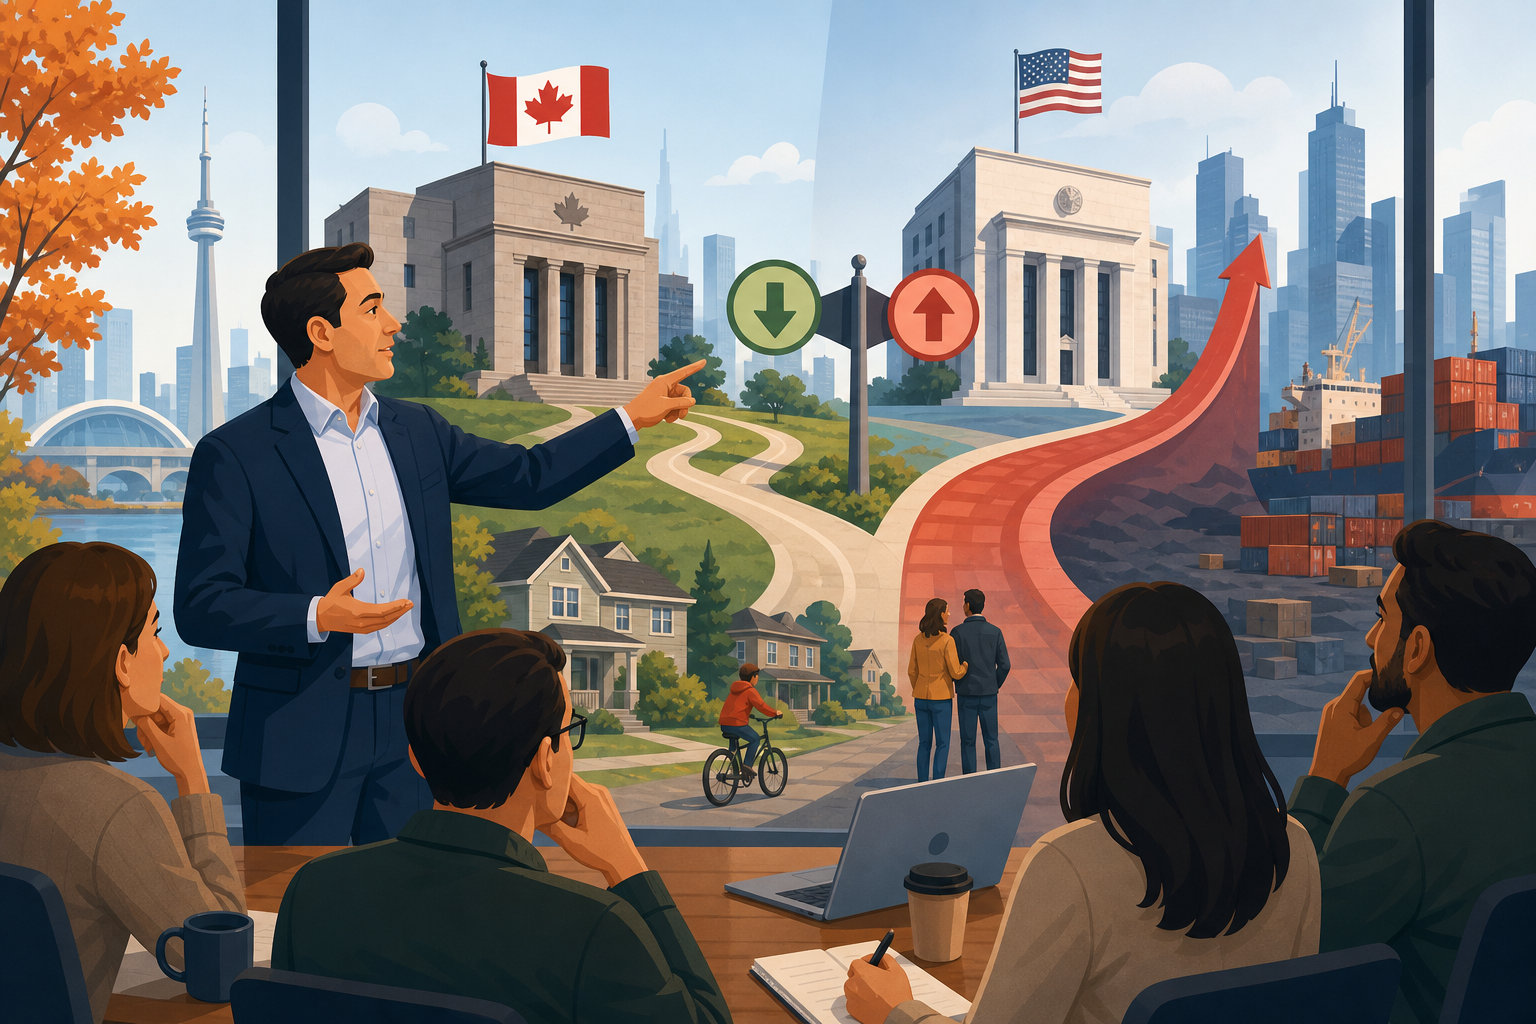
Derek Burleton sat across from a room of mortgage brokers in September 2026 and said something most of them weren't pricing in: the Bank of Canada doesn't have to raise rates just because the Federal Reserve does.
That matters, because the market has spent the better part of a year assuming the opposite. When the Fed hiked in March, bond traders moved Canadian yields up in lockstep. When the Fed signaled another possible increase in Q4, the futures curve for Canadian policy rates shifted the same direction. The logic runs through currency protection: if the BoC stands still while the Fed tightens, the loonie weakens, imports get pricier, inflation ticks back up, and the whole exercise falls apart. So the BoC follows. That's been the pattern for decades.
Burleton, TD's deputy chief economist, thinks that pattern is breaking. His argument isn't that the BoC will never hike again. It's that the case for doing so right now, in this economy, with this consumer balance sheet, isn't compelling enough to justify mimicking the Fed move for move.
The renewal cliff changes the arithmetic
Canadian mortgage holders renew every five years. American mortgage holders lock in for thirty. That difference rewrites the entire transmission mechanism for interest rate policy.
When the BoC raised rates from 0.25% starting in March 2022, reaching 5.00% in July 2023, those hikes didn't hit most borrowers immediately. They hit when the renewal notice arrived. And the renewal notices are arriving now. A homeowner who locked in a five-year fixed at 1.89% in 2021 is rolling into a new term at rates in the 4% to 5% range in 2026. That's a mortgage payment increase of $800 to $1,200 a month on a $500,000 loan, depending on the loan term length (the period over which you repay the loan, typically 25 to 30 years).
The Canadian consumer is already absorbing a rate shock the Fed's borrowers never experienced. The U.S. housing stock is largely insulated; mortgages written at 3% in 2021 are still paying 3% in 2026. The Canadian housing stock is being repriced in real time. The percentage of household income that goes toward debt payments like mortgages and loans each month in Canada is climbing without any new rate hikes at all, purely from renewals.
That acts as a natural brake. The BoC doesn't need to keep tightening to slow the economy when the renewals are doing the work for them.
What the loonie argument misses
The currency objection is real but overstated. A weaker Canadian dollar does push up import prices, but the inflation risk depends on what's driving the weakness. If the loonie is falling because the Canadian economy is cooling faster than the U.S. economy, that divergence itself suppresses domestic demand, which offsets some of the import-price pressure.
The BoC has room to let that trade-off play out, especially when the alternative is pushing already-stretched households into default or forced sales. The overnight rate sits at 2.25% as of September 2026, at the lower end of the BoC's estimated neutral range of 2.25% to 3.25%. Policy is restrictive. It doesn't need to get more restrictive just because the Fed is managing a different problem in a different economy with a different mortgage structure.
The housing bottom is in, but don't expect a bounce
Burleton also told brokers the housing market has likely bottomed out. Prices in most markets have stopped falling. Inventory has stabilized. Panic selling has cooled.
But a bottom is not a recovery. Edmonton's housing market has stabilized after declines from 2022 peaks, with prices holding steady for several quarters. That stability matters more than the direction for first-time buyers. A market that isn't moving is a market you can plan in. You know what you're paying. You know what you qualify for. Prices are stable, a marked contrast to the rapid appreciation that characterized 2021.
Burleton expects a grind ahead. Prices will inch up as employment holds and immigration continues, but the rapid appreciation that defined 2020 and 2022 isn't coming back anytime soon. Higher-for-longer rates ensure that. A slower recovery is a more predictable one, and predictability is what the market actually needs right now.
Markets that assume the BoC will mechanically track the Fed are betting on a monetary policy framework that no longer fits the data. The consumer in Canada is already tightening their belt without any help from Tiff Macklem. The case for another hike isn't compelling. Burleton is saying that out loud. The futures curve hasn't caught up yet.

Derek Burleton sat across from a room of mortgage brokers in September 2026 and said something most of them weren't pricing in: the Bank of Canada doesn't have to raise rates just because the Federal Reserve does.
That matters, because the market has spent the better part of a year assuming the opposite. When the Fed hiked in March, bond traders moved Canadian yields up in lockstep. When the Fed signaled another possible increase in Q4, the futures curve for Canadian policy rates shifted the same direction. The logic runs through currency protection: if the BoC stands still while the Fed tightens, the loonie weakens, imports get pricier, inflation ticks back up, and the whole exercise falls apart. So the BoC follows. That's been the pattern for decades.
Burleton, TD's deputy chief economist, thinks that pattern is breaking. His argument isn't that the BoC will never hike again. It's that the case for doing so right now, in this economy, with this consumer balance sheet, isn't compelling enough to justify mimicking the Fed move for move.
The renewal cliff changes the arithmetic
Canadian mortgage holders renew every five years. American mortgage holders lock in for thirty. That difference rewrites the entire transmission mechanism for interest rate policy.
When the BoC raised rates from 0.25% starting in March 2022, reaching 5.00% in July 2023, those hikes didn't hit most borrowers immediately. They hit when the renewal notice arrived. And the renewal notices are arriving now. A homeowner who locked in a five-year fixed at 1.89% in 2021 is rolling into a new term at rates in the 4% to 5% range in 2026. That's a mortgage payment increase of $800 to $1,200 a month on a $500,000 loan, depending on the loan term length (the period over which you repay the loan, typically 25 to 30 years).
The Canadian consumer is already absorbing a rate shock the Fed's borrowers never experienced. The U.S. housing stock is largely insulated; mortgages written at 3% in 2021 are still paying 3% in 2026. The Canadian housing stock is being repriced in real time. The percentage of household income that goes toward debt payments like mortgages and loans each month in Canada is climbing without any new rate hikes at all, purely from renewals.
That acts as a natural brake. The BoC doesn't need to keep tightening to slow the economy when the renewals are doing the work for them.
What the loonie argument misses
The currency objection is real but overstated. A weaker Canadian dollar does push up import prices, but the inflation risk depends on what's driving the weakness. If the loonie is falling because the Canadian economy is cooling faster than the U.S. economy, that divergence itself suppresses domestic demand, which offsets some of the import-price pressure.
The BoC has room to let that trade-off play out, especially when the alternative is pushing already-stretched households into default or forced sales. The overnight rate sits at 2.25% as of September 2026, at the lower end of the BoC's estimated neutral range of 2.25% to 3.25%. Policy is restrictive. It doesn't need to get more restrictive just because the Fed is managing a different problem in a different economy with a different mortgage structure.
The housing bottom is in, but don't expect a bounce
Burleton also told brokers the housing market has likely bottomed out. Prices in most markets have stopped falling. Inventory has stabilized. Panic selling has cooled.
But a bottom is not a recovery. Edmonton's housing market has stabilized after declines from 2022 peaks, with prices holding steady for several quarters. That stability matters more than the direction for first-time buyers. A market that isn't moving is a market you can plan in. You know what you're paying. You know what you qualify for. Prices are stable, a marked contrast to the rapid appreciation that characterized 2021.
Burleton expects a grind ahead. Prices will inch up as employment holds and immigration continues, but the rapid appreciation that defined 2020 and 2022 isn't coming back anytime soon. Higher-for-longer rates ensure that. A slower recovery is a more predictable one, and predictability is what the market actually needs right now.
Markets that assume the BoC will mechanically track the Fed are betting on a monetary policy framework that no longer fits the data. The consumer in Canada is already tightening their belt without any help from Tiff Macklem. The case for another hike isn't compelling. Burleton is saying that out loud. The futures curve hasn't caught up yet.
Sources
Read Next
A One-Time Capital Gain Can Trigger Alternative Minimum Tax Even for Average Canadians
The S&P Looks Stable Because You're Measuring the Wrong Volatility
Clearwater Seafoods Family Backs Prefab Housing as Construction Speed Solution
South Bow sees private equity interest in Prairie Connector following Carney's new mega-deduction announcement