South Bow sees private equity interest in Prairie Connector following Carney's new mega-deduction announcement
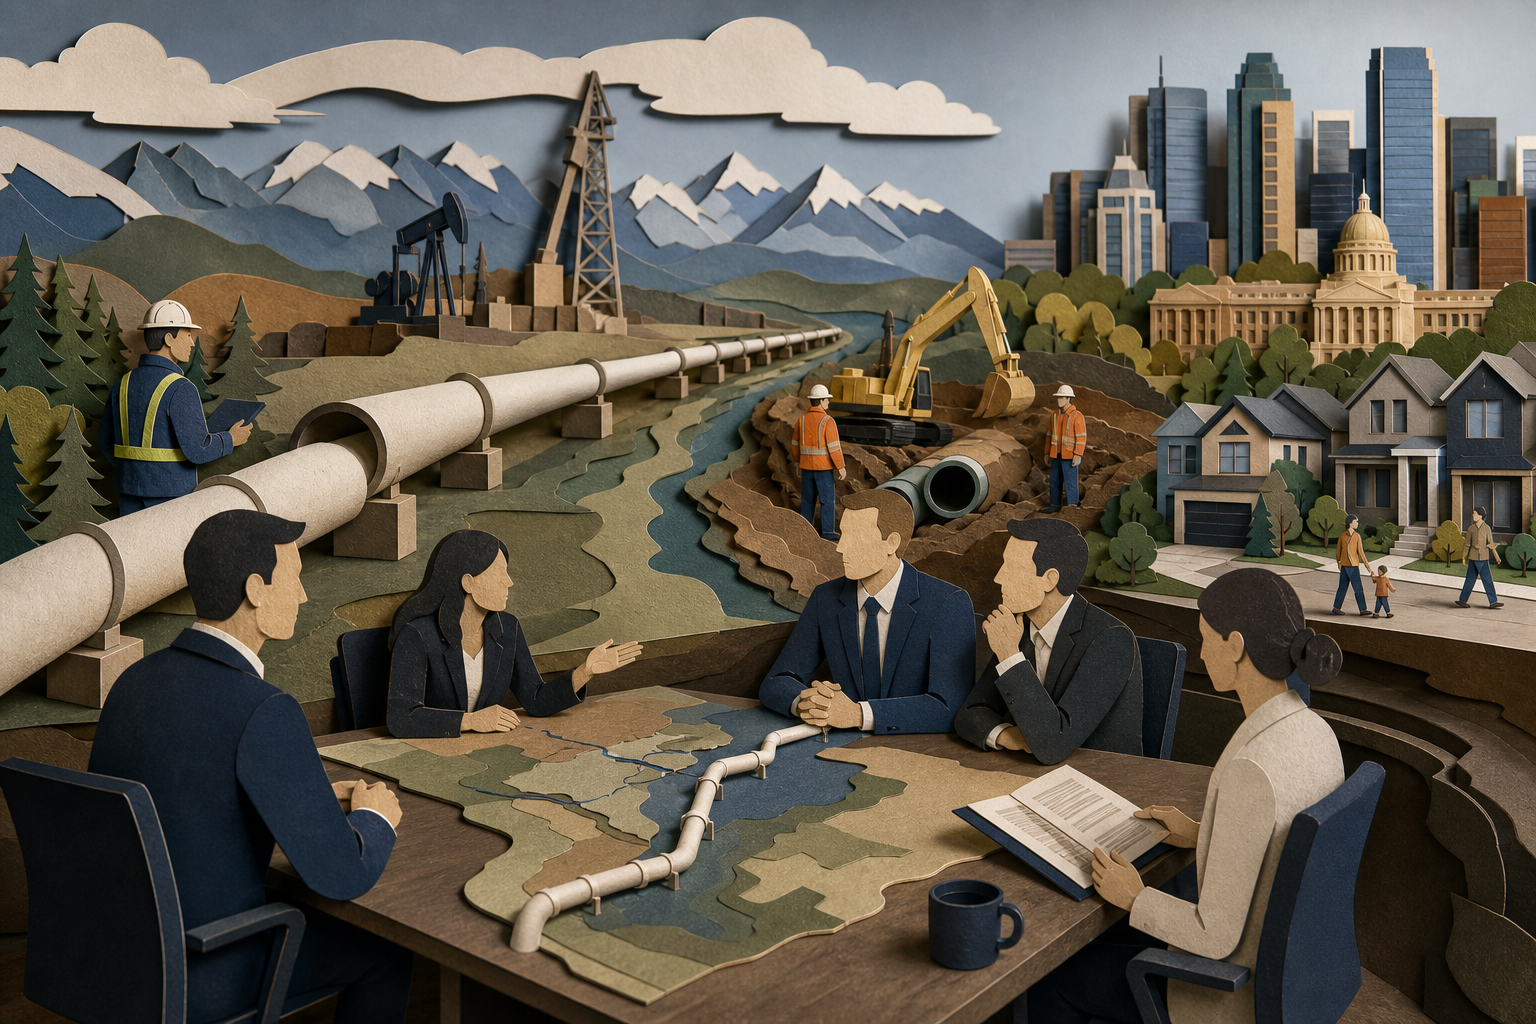
Tax breaks do not build pipelines. They change the math just enough that someone else might write the check. South Bow Corp. is a Calgary-based pipeline operator spun off from TC Energy. It is now fielding calls from private equity managers interested in buying a stake in the Prairie Connector expansion project. The company attributes this interest directly to the federal government's proposed "mega-deduction" announced in September 2026 under Prime Minister Mark Carney.
The deduction works by allowing companies to write off the costs of pipelines, facilities, and equipment at an accelerated rate, keeping more of their earnings in-house if they commit capital to projects the government deems nationally significant. For South Bow, that means the Prairie Connector, a proposed expansion linking production in Northern Alberta to refineries on the U.S. Gulf Coast, crosses the threshold from marginally viable to worth the capital deployment conversation. The shift is not subtle. Projects of this scale typically require internal rates of return in the 10% to 15% range to attract institutional money. A tax break that pulls forward deductions by several years can move a borderline project over that line.
Why private equity showed up now
Infrastructure funds treat pipelines as toll roads: predictable volume, contracted rates, cash flow that compounds quietly for decades. But Canadian energy projects carry regulatory risk that scares off some of that capital. Environmental assessments stretch timelines. Indigenous consultation processes add layers of uncertainty. The mega-deduction lowers the cost of waiting through these processes.
South Bow's CEO has confirmed the company is exploring hybrid financing, including equity sales to private fund managers. The logic is direct. Selling a minority stake reduces South Bow's debt load while bringing in partners whose returns depend on volume shipped, not whether construction stays on schedule. For the buyer, it is a "mature asset" play even before the pipe is in the ground, low operational complexity, geographically stable, insulated from commodity swings by long-term shipper agreements.
The 2026 task force recommendations frame this as a supply-side incentive rather than a subsidy. The government allows companies to keep more of what they earn, on the condition they deploy it into projects the government wants built. The distinction matters for optics, less so for the balance sheet. Either way, the capital cost of the Prairie Connector drops.
What Edmonton sees from this
The Prairie Connector is a signal about labour market opportunity. Construction projects of this scale pull trades workers from across Western Canada, and the engineering work clusters in hubs like Edmonton where pipeline operators already maintain control centres. With Federal Reserve rates still elevated relative to the 2010s, spending on pipelines and facilities has been muted across North America. A greenlit project reverses that, even temporarily.
Move-up buyers and investors tracking Edmonton's economy watch energy pipeline announcements because they correlate with job stability in high-income brackets. A pipeline project indicates that capital is moving again.
The risk no one wants to name
The mega-deduction only helps if South Bow turns a profit. If global oil prices collapse or Canadian production plateaus, the tax break becomes theoretical. If companies earn no taxable income, they cannot deduct expenses. The unspoken contingency buried in every private equity pitch is that the model works if the underlying commodity cooperates.
Regulatory delays remain the other variable. Even with federal tax policy aligned, the Prairie Connector still faces provincial environmental assessments and multi-year consultation timelines. The mega-deduction accelerates the financial decision. It does not accelerate the permitting process. Private equity managers are betting that South Bow can navigate the red tape. If they are wrong, the tax break just made the wait cheaper.

Tax breaks do not build pipelines. They change the math just enough that someone else might write the check. South Bow Corp. is a Calgary-based pipeline operator spun off from TC Energy. It is now fielding calls from private equity managers interested in buying a stake in the Prairie Connector expansion project. The company attributes this interest directly to the federal government's proposed "mega-deduction" announced in September 2026 under Prime Minister Mark Carney.
The deduction works by allowing companies to write off the costs of pipelines, facilities, and equipment at an accelerated rate, keeping more of their earnings in-house if they commit capital to projects the government deems nationally significant. For South Bow, that means the Prairie Connector, a proposed expansion linking production in Northern Alberta to refineries on the U.S. Gulf Coast, crosses the threshold from marginally viable to worth the capital deployment conversation. The shift is not subtle. Projects of this scale typically require internal rates of return in the 10% to 15% range to attract institutional money. A tax break that pulls forward deductions by several years can move a borderline project over that line.
Why private equity showed up now
Infrastructure funds treat pipelines as toll roads: predictable volume, contracted rates, cash flow that compounds quietly for decades. But Canadian energy projects carry regulatory risk that scares off some of that capital. Environmental assessments stretch timelines. Indigenous consultation processes add layers of uncertainty. The mega-deduction lowers the cost of waiting through these processes.
South Bow's CEO has confirmed the company is exploring hybrid financing, including equity sales to private fund managers. The logic is direct. Selling a minority stake reduces South Bow's debt load while bringing in partners whose returns depend on volume shipped, not whether construction stays on schedule. For the buyer, it is a "mature asset" play even before the pipe is in the ground, low operational complexity, geographically stable, insulated from commodity swings by long-term shipper agreements.
The 2026 task force recommendations frame this as a supply-side incentive rather than a subsidy. The government allows companies to keep more of what they earn, on the condition they deploy it into projects the government wants built. The distinction matters for optics, less so for the balance sheet. Either way, the capital cost of the Prairie Connector drops.
What Edmonton sees from this
The Prairie Connector is a signal about labour market opportunity. Construction projects of this scale pull trades workers from across Western Canada, and the engineering work clusters in hubs like Edmonton where pipeline operators already maintain control centres. With Federal Reserve rates still elevated relative to the 2010s, spending on pipelines and facilities has been muted across North America. A greenlit project reverses that, even temporarily.
Move-up buyers and investors tracking Edmonton's economy watch energy pipeline announcements because they correlate with job stability in high-income brackets. A pipeline project indicates that capital is moving again.
The risk no one wants to name
The mega-deduction only helps if South Bow turns a profit. If global oil prices collapse or Canadian production plateaus, the tax break becomes theoretical. If companies earn no taxable income, they cannot deduct expenses. The unspoken contingency buried in every private equity pitch is that the model works if the underlying commodity cooperates.
Regulatory delays remain the other variable. Even with federal tax policy aligned, the Prairie Connector still faces provincial environmental assessments and multi-year consultation timelines. The mega-deduction accelerates the financial decision. It does not accelerate the permitting process. Private equity managers are betting that South Bow can navigate the red tape. If they are wrong, the tax break just made the wait cheaper.
Sources
Read Next
A One-Time Capital Gain Can Trigger Alternative Minimum Tax Even for Average Canadians
The S&P Looks Stable Because You're Measuring the Wrong Volatility
Clearwater Seafoods Family Backs Prefab Housing as Construction Speed Solution
Why One TSX Stock Gained 13% While Canadian Utilities and REITs Fell