One Bigger Home or Two Smaller Ones: Weighing Multigenerational Living in Alberta
More than half of prospective Canadian buyers say they would consider living with extended family to make a purchase work, according to RBC's latest homebuyer poll, released in October 2026. Nearly three-quarters of upcoming first-time buyers also say they want a home they can stay in longer. In Edmonton, those two ideas often meet in one practical question: should a family pool resources into one larger property, or buy two separate places?
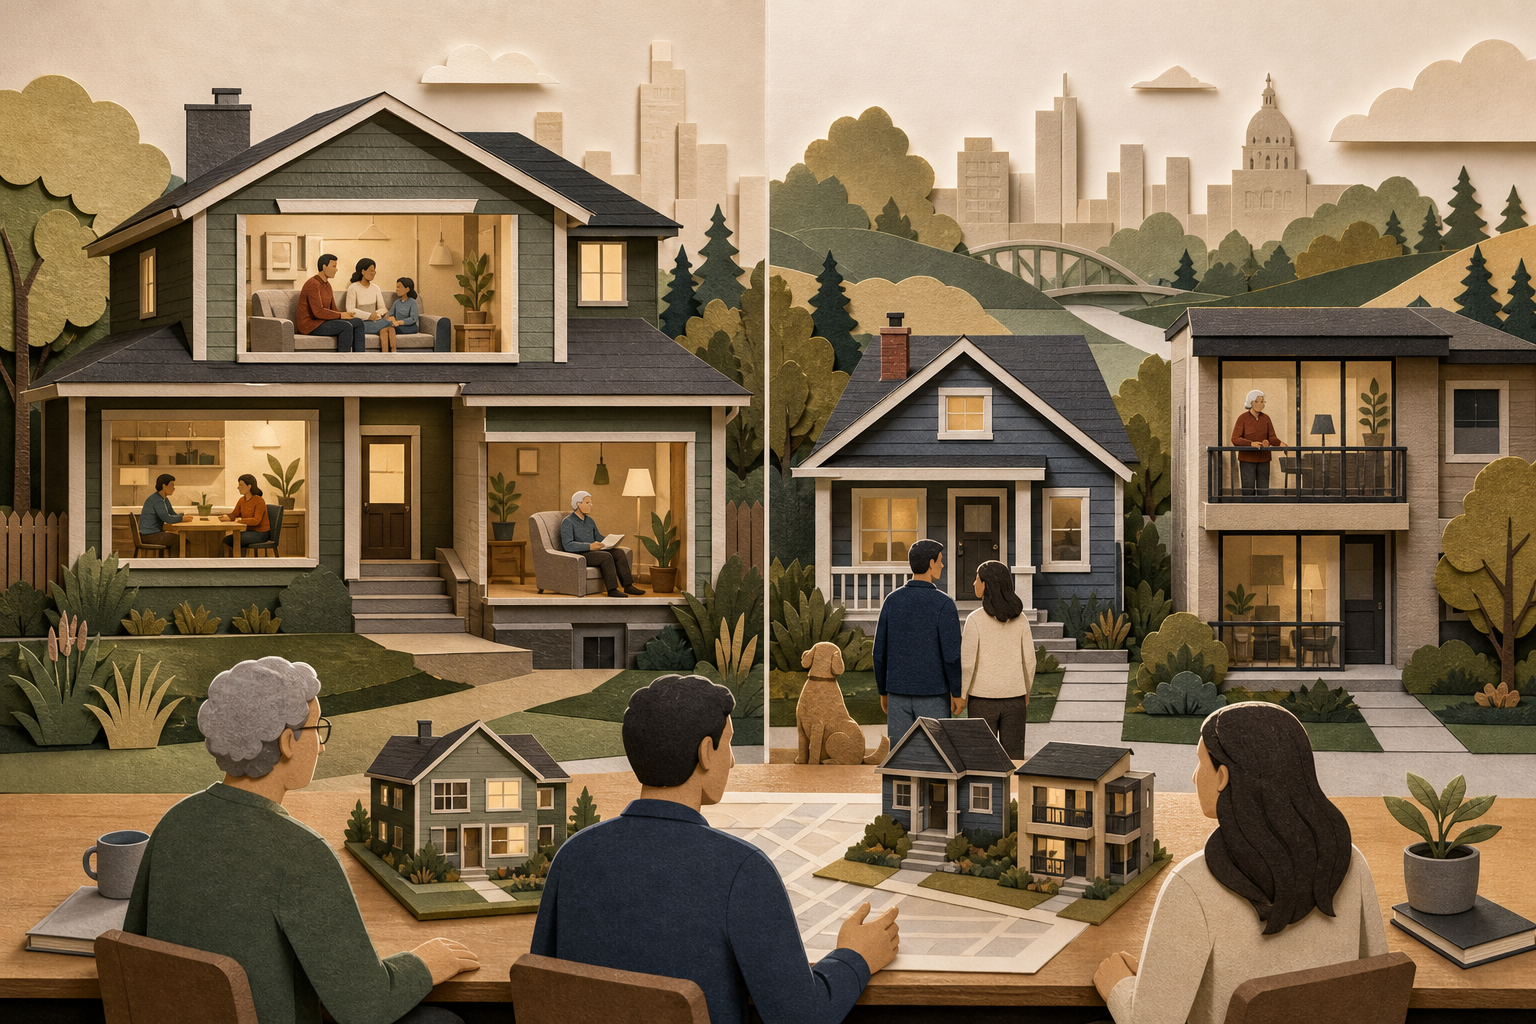
To compare fairly, take one hypothetical family. An adult couple and one retired parent each have some savings and some income. They plan to stay put for about ten years. Option A is one larger house with a legal secondary suite or garden suite. Option B is two smaller homes, for example a starter house for the couple and a condo for the parent. Each option is judged on the same five things: upfront costs, monthly costs, mortgage qualifying, flexibility to exit, and day-to-day living.
Upfront costs
Alberta has no land transfer tax, so the gap here is smaller than in some provinces. Option B still means two of everything at closing: two lawyers, two inspections, two appraisals and two sets of registration fees. Option A means one set, though a home with a legal suite usually costs more to buy. If the family builds a suite instead, the federal Multigenerational Home Renovation Tax Credit can return 15% of up to $50,000 in eligible costs, a maximum of $7,500. It only applies when the unit is for a qualifying senior or an adult eligible for the disability tax credit.
Monthly costs
This is where one home has a calculable edge. Here is an illustration with made-up numbers, not current prices. Suppose fixed overhead (insurance, base utility charges and a maintenance reserve) runs $400 a month per home. Suppose the single larger home runs $550. Two homes cost $800, so the gap is $250 a month, $3,000 a year, or $30,000 over ten years. Condo fees in Option B would widen that gap. Use your own quotes, because the saving depends entirely on the real properties.
Qualifying for the mortgage
Lenders can often count part of the rental income from a legal suite when deciding how much you qualify for. Rent from a parent counts only if it is a real, documented arrangement, and lender policies differ. Many families qualify by putting the parent on the mortgage as a co-borrower instead. In Option B, each household qualifies on its own. That can be harder for a retiree, but no one's debt depends on anyone else. "Legal" matters here. In Edmonton, a suite needs proper permits and must meet fire and building code to count. The city's renewed zoning bylaw generally allows secondary and garden suites in residential areas, but permits are still required.
Flexibility and exit
Option B wins this one clearly. If the parent later needs care, or the couple wants to relocate for work, one home sells without touching the other. With Option A, every change involves everyone. Title choice matters too. Joint tenancy and tenants in common treat a death or a sale very differently. A written co-ownership agreement that covers buyouts and who pays for repairs is worth the legal fee. Renting part of a home can also affect your principal residence exemption, so get tax advice before you set up the arrangement.
Living together
Some benefits have no reliable price: a parent nearby to help with kids, or adult children close by as a parent ages. Some costs have no price either: less privacy, shared decisions, and family friction. Be honest about both.
Which suits whom
One larger home suits families who expect to stay together for many years, who will build or buy a legal suite, and who have agreed in writing how they would unwind it. It suits even better when the parent qualifies for the renovation credit. Two smaller homes suit families who value independence, expect needs to change within a few years, or have one member who might need to sell on short notice.
What would change the answer? If real quotes show only a small overhead gap, the case for Option A weakens. If the suite fails code or the permit review, its qualifying advantage disappears. And if the parent cannot qualify alone, Option B may not be possible at all. Run both options through a lender before you choose.



More than half of prospective Canadian buyers say they would consider living with extended family to make a purchase work, according to RBC's latest homebuyer poll, released in October 2026. Nearly three-quarters of upcoming first-time buyers also say they want a home they can stay in longer. In Edmonton, those two ideas often meet in one practical question: should a family pool resources into one larger property, or buy two separate places?
To compare fairly, take one hypothetical family. An adult couple and one retired parent each have some savings and some income. They plan to stay put for about ten years. Option A is one larger house with a legal secondary suite or garden suite. Option B is two smaller homes, for example a starter house for the couple and a condo for the parent. Each option is judged on the same five things: upfront costs, monthly costs, mortgage qualifying, flexibility to exit, and day-to-day living.
Upfront costs
Alberta has no land transfer tax, so the gap here is smaller than in some provinces. Option B still means two of everything at closing: two lawyers, two inspections, two appraisals and two sets of registration fees. Option A means one set, though a home with a legal suite usually costs more to buy. If the family builds a suite instead, the federal Multigenerational Home Renovation Tax Credit can return 15% of up to $50,000 in eligible costs, a maximum of $7,500. It only applies when the unit is for a qualifying senior or an adult eligible for the disability tax credit.
Monthly costs
This is where one home has a calculable edge. Here is an illustration with made-up numbers, not current prices. Suppose fixed overhead (insurance, base utility charges and a maintenance reserve) runs $400 a month per home. Suppose the single larger home runs $550. Two homes cost $800, so the gap is $250 a month, $3,000 a year, or $30,000 over ten years. Condo fees in Option B would widen that gap. Use your own quotes, because the saving depends entirely on the real properties.
Qualifying for the mortgage
Lenders can often count part of the rental income from a legal suite when deciding how much you qualify for. Rent from a parent counts only if it is a real, documented arrangement, and lender policies differ. Many families qualify by putting the parent on the mortgage as a co-borrower instead. In Option B, each household qualifies on its own. That can be harder for a retiree, but no one's debt depends on anyone else. "Legal" matters here. In Edmonton, a suite needs proper permits and must meet fire and building code to count. The city's renewed zoning bylaw generally allows secondary and garden suites in residential areas, but permits are still required.
Flexibility and exit
Option B wins this one clearly. If the parent later needs care, or the couple wants to relocate for work, one home sells without touching the other. With Option A, every change involves everyone. Title choice matters too. Joint tenancy and tenants in common treat a death or a sale very differently. A written co-ownership agreement that covers buyouts and who pays for repairs is worth the legal fee. Renting part of a home can also affect your principal residence exemption, so get tax advice before you set up the arrangement.
Living together
Some benefits have no reliable price: a parent nearby to help with kids, or adult children close by as a parent ages. Some costs have no price either: less privacy, shared decisions, and family friction. Be honest about both.
Which suits whom
One larger home suits families who expect to stay together for many years, who will build or buy a legal suite, and who have agreed in writing how they would unwind it. It suits even better when the parent qualifies for the renovation credit. Two smaller homes suit families who value independence, expect needs to change within a few years, or have one member who might need to sell on short notice.
What would change the answer? If real quotes show only a small overhead gap, the case for Option A weakens. If the suite fails code or the permit review, its qualifying advantage disappears. And if the parent cannot qualify alone, Option B may not be possible at all. Run both options through a lender before you choose.
Read Next
Five Money Checks Canadian Snowbirds Should Finish Before Heading South
Canadian Bank Security Assumes a Human Is Logging In. AI Agents Break That
Before Storm Winds Arrive, Turn 5 Yard Hazards Into Protective Buffers
A 25 Basis Point Hike Doesn't Erase Variable's Long-Run Edge Over Fixed