Lauren van den Berg Leaves Mortgage Professionals Canada: What the Board Decides Next
Van den Berg is staying on through a transition period, and the board of Mortgage Professionals Canada has not yet named an interim leader or set a date for hiring a permanent one. So for now the organization is between leaders, with the outgoing CEO helping to hand things over while the directors work out what comes next.
For most people buying a home in Edmonton, the name Mortgage Professionals Canada may not mean much. It is the national industry association for mortgage brokers, and it also represents lenders and insurers. It is not a regulator. It does not set interest rates, approve mortgages, or write the qualifying rules. Its job is to speak for the industry when federal rules are being made, mostly in Ottawa, and to argue for changes its members think would help borrowers and the business.
That advocacy matters more than it might seem, because federal rules decide how much you can borrow.
Why the association's agenda reaches your budget
The clearest example is the mortgage stress test. Under the federal banking regulator's rules for uninsured mortgages, you have to qualify at your contract rate plus 200 basis points, or 5.25 percent, whichever is higher. A basis point is one hundredth of a percent, so 200 basis points means two full percentage points. If your lender offers you 4.5 percent, you are tested as if you were paying 6.5 percent. The test shrinks the maximum loan you can qualify for, even when you could comfortably handle the real payment.
During her time as CEO, van den Berg was a steady voice arguing that the test keeps some qualified buyers out of the market and should be reformed. The association has also pushed for longer amortizations. Amortization is the number of years it takes to pay off the loan. Stretching it lowers the monthly payment, though you pay more interest overall. In December 2024, Ottawa allowed 30-year amortizations on insured mortgages for first-time buyers and anyone buying a new build. The association has argued for wider access than that.
None of these positions became policy just because an association asked. But they shape the discussion, and whoever leads the group decides which issues get pushed hardest.
What the board is actually deciding
The board has a few choices to make in sequence. First, it needs to decide who runs the organization day to day once the handover period ends, which usually means naming an interim leader. Second, it has to run a search for a permanent CEO. Third, and less visibly, it has to decide what kind of leader it wants, because that choice signals where the association's priorities are heading.
A leader with a strong government relations background will likely keep the focus on federal lending rules. Someone with a technology or operations background might focus more on the digital work the association has done internally in recent years. Neither choice changes anything for borrowers right away.
There is a practical cost to a gap at the top. Advocacy depends on relationships and steady follow-up, and a leadership change can slow the pace of new proposals heading into a federal budget cycle. That is a real consideration, but it affects the timing of possible future changes, not the rules you are working under today.
What stays the same in Alberta
If you are working with a mortgage broker in Edmonton, nothing about their licence or your protections changes. Brokers here are licensed and overseen by the Real Estate Council of Alberta. The stress test still applies in the same way. Your rate still depends on the Bank of Canada, bond markets, and the lender you choose. Down payment rules are unchanged too: insured purchases still require 5 percent on the first $500,000 and 10 percent on the portion above that.
One question worth watching is whether the next leader speaks to markets like ours. National housing debates tend to centre on Toronto and Vancouver, where prices relative to income are far higher. In Edmonton, the same rules land differently. A buyer here may have solid income and a reasonable target price and still find that the stress test pulls their approval below what they could actually carry each month. An association that makes that case clearly would be speaking for a lot of Alberta buyers, whether they are buying their first home, moving up, or adding a rental property.


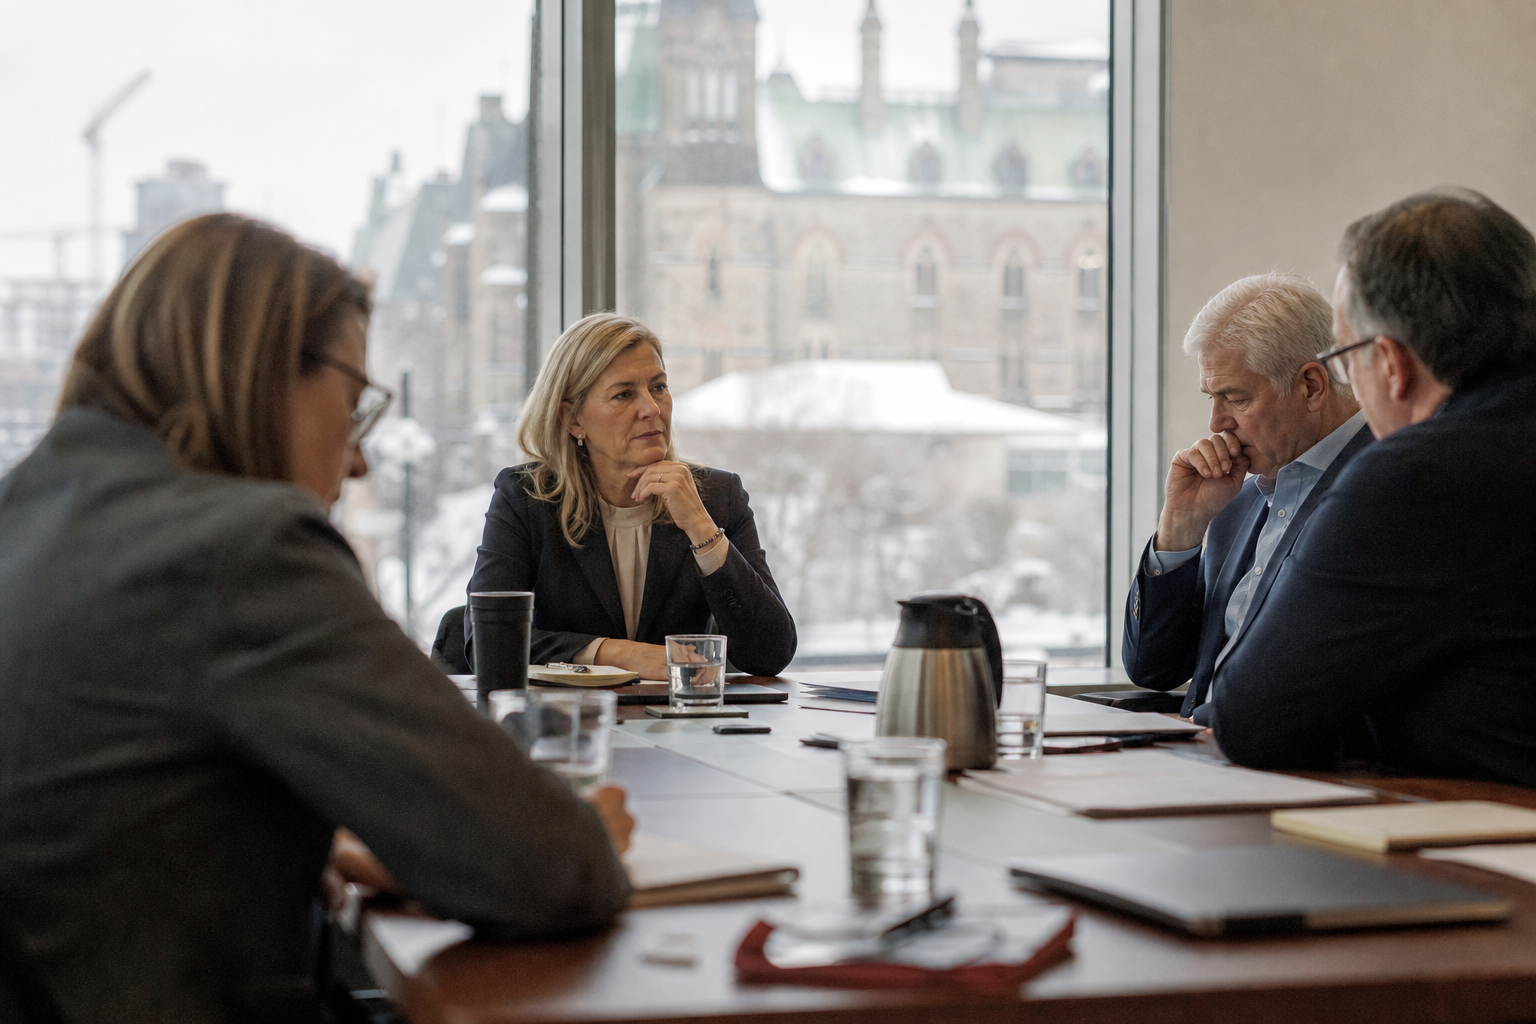

Van den Berg is staying on through a transition period, and the board of Mortgage Professionals Canada has not yet named an interim leader or set a date for hiring a permanent one. So for now the organization is between leaders, with the outgoing CEO helping to hand things over while the directors work out what comes next.
For most people buying a home in Edmonton, the name Mortgage Professionals Canada may not mean much. It is the national industry association for mortgage brokers, and it also represents lenders and insurers. It is not a regulator. It does not set interest rates, approve mortgages, or write the qualifying rules. Its job is to speak for the industry when federal rules are being made, mostly in Ottawa, and to argue for changes its members think would help borrowers and the business.
That advocacy matters more than it might seem, because federal rules decide how much you can borrow.
Why the association's agenda reaches your budget
The clearest example is the mortgage stress test. Under the federal banking regulator's rules for uninsured mortgages, you have to qualify at your contract rate plus 200 basis points, or 5.25 percent, whichever is higher. A basis point is one hundredth of a percent, so 200 basis points means two full percentage points. If your lender offers you 4.5 percent, you are tested as if you were paying 6.5 percent. The test shrinks the maximum loan you can qualify for, even when you could comfortably handle the real payment.
During her time as CEO, van den Berg was a steady voice arguing that the test keeps some qualified buyers out of the market and should be reformed. The association has also pushed for longer amortizations. Amortization is the number of years it takes to pay off the loan. Stretching it lowers the monthly payment, though you pay more interest overall. In December 2024, Ottawa allowed 30-year amortizations on insured mortgages for first-time buyers and anyone buying a new build. The association has argued for wider access than that.
None of these positions became policy just because an association asked. But they shape the discussion, and whoever leads the group decides which issues get pushed hardest.
What the board is actually deciding
The board has a few choices to make in sequence. First, it needs to decide who runs the organization day to day once the handover period ends, which usually means naming an interim leader. Second, it has to run a search for a permanent CEO. Third, and less visibly, it has to decide what kind of leader it wants, because that choice signals where the association's priorities are heading.
A leader with a strong government relations background will likely keep the focus on federal lending rules. Someone with a technology or operations background might focus more on the digital work the association has done internally in recent years. Neither choice changes anything for borrowers right away.
There is a practical cost to a gap at the top. Advocacy depends on relationships and steady follow-up, and a leadership change can slow the pace of new proposals heading into a federal budget cycle. That is a real consideration, but it affects the timing of possible future changes, not the rules you are working under today.
What stays the same in Alberta
If you are working with a mortgage broker in Edmonton, nothing about their licence or your protections changes. Brokers here are licensed and overseen by the Real Estate Council of Alberta. The stress test still applies in the same way. Your rate still depends on the Bank of Canada, bond markets, and the lender you choose. Down payment rules are unchanged too: insured purchases still require 5 percent on the first $500,000 and 10 percent on the portion above that.
One question worth watching is whether the next leader speaks to markets like ours. National housing debates tend to centre on Toronto and Vancouver, where prices relative to income are far higher. In Edmonton, the same rules land differently. A buyer here may have solid income and a reasonable target price and still find that the stress test pulls their approval below what they could actually carry each month. An association that makes that case clearly would be speaking for a lot of Alberta buyers, whether they are buying their first home, moving up, or adding a rental property.
Read Next
Five Money Checks Canadian Snowbirds Should Finish Before Heading South
Canadian Bank Security Assumes a Human Is Logging In. AI Agents Break That
Before Storm Winds Arrive, Turn 5 Yard Hazards Into Protective Buffers
A 25 Basis Point Hike Doesn't Erase Variable's Long-Run Edge Over Fixed