Groupe Dynamite Raises Guidance While Transat Bleeds: What Two Diverging Stocks Say About Canada's Recovery
Dynamite sold 31.5% more online this quarter than the same stretch last year, with Gen Z customers driving the surge through mobile checkout. Transat, meanwhile, grounded six more planes for engine inspections it cannot afford and may not recover from.
Two public companies. Same economy. Opposite trajectories. The divergence isn't random.
The fashion retailer that found its lane
Groupe Dynamite Inc., the Montreal company behind Garage and Dynamite, raised its full-year guidance in September 2026 following stronger-than-expected performance in both Canada and the U.S. Adjusted EBITDA margins cleared analyst expectations, powered by double-digit digital growth and lean inventory management. The company's bet on mobile-first commerce for women aged 18 to 28 is paying off in a climate where discretionary spending has bifurcated sharply: luxury and discount are winning, and the middle is stagnant.
GDI's success hinges on price positioning that reads as aspirational without requiring a credit decision. A $68 going-out top is high enough to signal quality, low enough to avoid the "do I really need this" conversation most Canadians are having with themselves in mid-2026. That's the lipstick effect at work, even as big-ticket purchases like flights and hotels face headwinds.
The U.S. expansion is the other variable. For Canadian retailers, domestic performance validates the concept. U.S. penetration earns the valuation multiple. GDI is opening stores in the Sunbelt, where population growth and younger demographics align with its product. The company's same-store sales momentum in Texas and Florida suggests the brand translates.
The airline with no room left
Transat A.T. Inc. reported another quarterly loss in 2026, weighed down by capacity constraints tied to its Airbus A321neoLR fleet. The Pratt & Whitney geared turbofan engines on those planes require recurring inspections tied to a global manufacturing defect Transat had no part in creating. The inspections ground planes for weeks at a time. Transat's fleet is small enough that losing six aircraft materially cuts available seat miles and revenue.
The leisure travel market Transat serves remains strong in raw demand terms, but the carrier is losing share to Air Canada and WestJet, both of which have more operational redundancy and can absorb similar engine issues without bleeding cash. Transat's liquidity position has tightened. Management has acknowledged the balance sheet as a constraint on growth, which in airline economics is another way of saying the company cannot compete.
Fuel volatility adds to the margin pressure, but fuel is a problem every carrier faces. The difference is that Transat has no buffer. A mid-sized airline with a fragile balance sheet and a maintenance backlog it cannot control is operating inside a very narrow envelope. One more external shock and the acquisition conversations that have circulated for years become the only exit.
What the split says about recovery
The "mixed picture" language that appears in every economic update is doing real work here. Canada's economy in 2026 splits along several decoupling lines.
Discretionary retail that targets affordable luxury and social-occasion wear is finding buyers. Younger consumers are spending on clothes, beauty, and going-out categories even as they pull back on travel and durables. Younger consumers are reallocating toward lower-ticket dopamine--a $68 top, a coffee, an event--and away from high-commitment purchases that lock up savings or require financing.
Travel demand is high, but supply-side breakdowns in aircraft manufacturing and parts availability mean demand alone does not translate to profitability for smaller carriers. Transat faces an operational fragility problem in an industry where scale and balance-sheet depth have become survival requirements.
Grocery, for context, sits somewhere in between. Empire Co. grew sales and raised its dividend by 10.2% in 2026, but the sector faces sustained political pressure on pricing and margin. Success in grocery now means growing through discount banners like FreshCo and using loyalty programs like Scene+ as data tools to prevent store-switching. Growth comes through defensive moves: expanding discount counters, tightening margin controls, using member card data to watch which customers are switching to competitors.
The recovery is real for companies that found product-market fit in the current environment. It is not real for companies still structured for 2019.


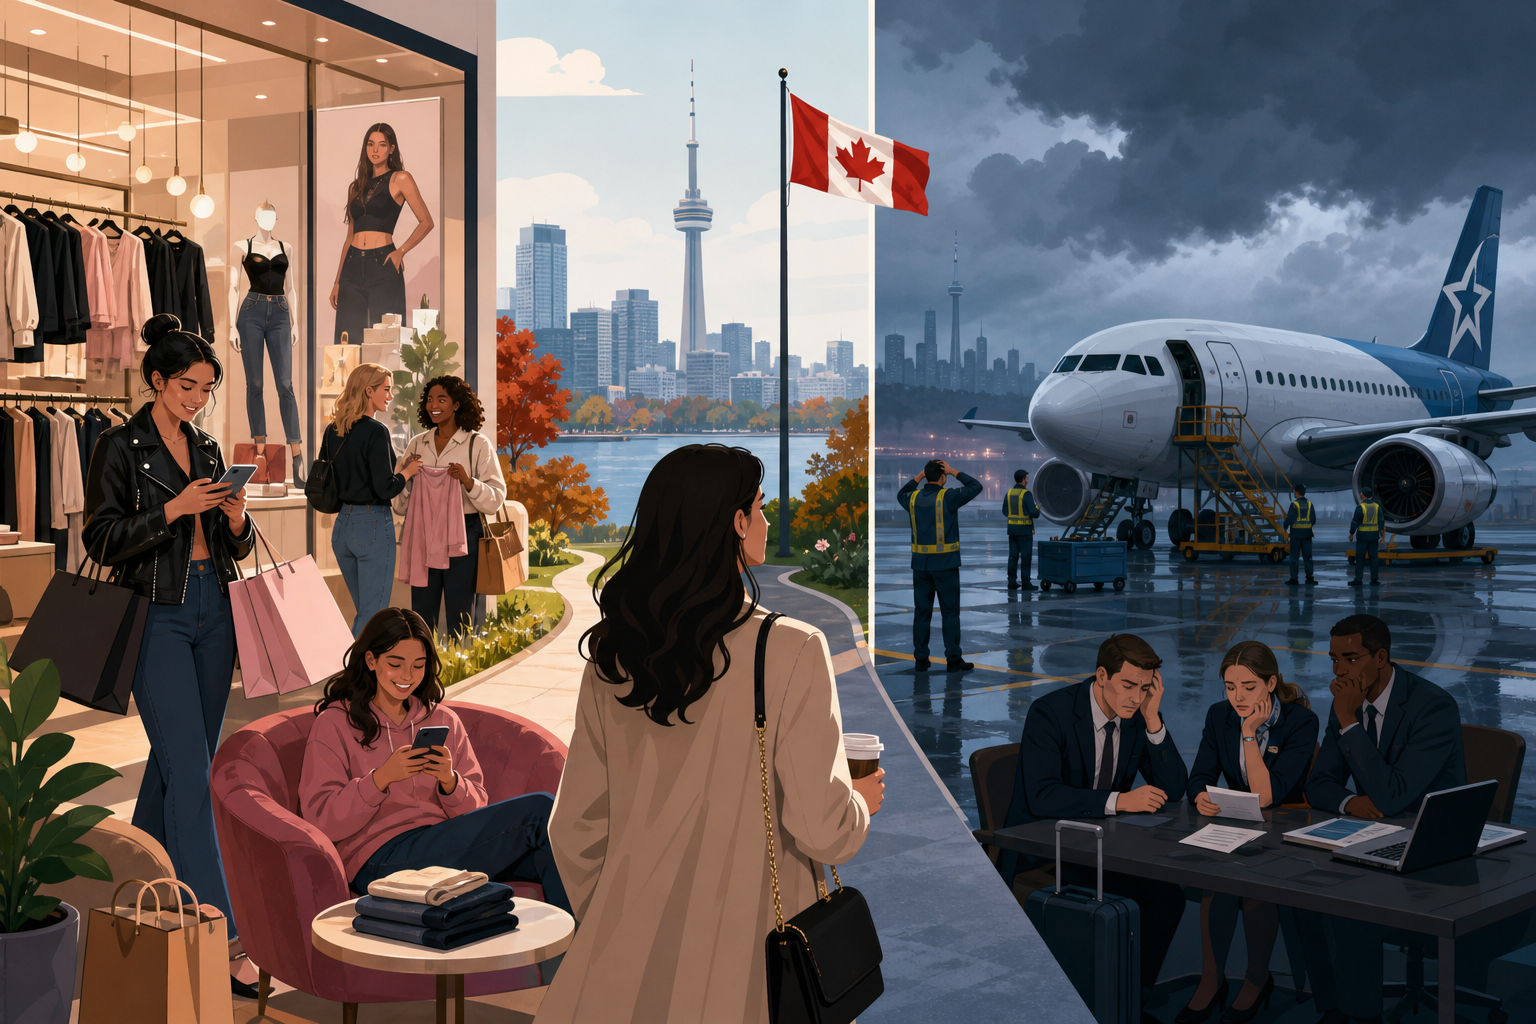

Dynamite sold 31.5% more online this quarter than the same stretch last year, with Gen Z customers driving the surge through mobile checkout. Transat, meanwhile, grounded six more planes for engine inspections it cannot afford and may not recover from.
Two public companies. Same economy. Opposite trajectories. The divergence isn't random.
The fashion retailer that found its lane
Groupe Dynamite Inc., the Montreal company behind Garage and Dynamite, raised its full-year guidance in September 2026 following stronger-than-expected performance in both Canada and the U.S. Adjusted EBITDA margins cleared analyst expectations, powered by double-digit digital growth and lean inventory management. The company's bet on mobile-first commerce for women aged 18 to 28 is paying off in a climate where discretionary spending has bifurcated sharply: luxury and discount are winning, and the middle is stagnant.
GDI's success hinges on price positioning that reads as aspirational without requiring a credit decision. A $68 going-out top is high enough to signal quality, low enough to avoid the "do I really need this" conversation most Canadians are having with themselves in mid-2026. That's the lipstick effect at work, even as big-ticket purchases like flights and hotels face headwinds.
The U.S. expansion is the other variable. For Canadian retailers, domestic performance validates the concept. U.S. penetration earns the valuation multiple. GDI is opening stores in the Sunbelt, where population growth and younger demographics align with its product. The company's same-store sales momentum in Texas and Florida suggests the brand translates.
The airline with no room left
Transat A.T. Inc. reported another quarterly loss in 2026, weighed down by capacity constraints tied to its Airbus A321neoLR fleet. The Pratt & Whitney geared turbofan engines on those planes require recurring inspections tied to a global manufacturing defect Transat had no part in creating. The inspections ground planes for weeks at a time. Transat's fleet is small enough that losing six aircraft materially cuts available seat miles and revenue.
The leisure travel market Transat serves remains strong in raw demand terms, but the carrier is losing share to Air Canada and WestJet, both of which have more operational redundancy and can absorb similar engine issues without bleeding cash. Transat's liquidity position has tightened. Management has acknowledged the balance sheet as a constraint on growth, which in airline economics is another way of saying the company cannot compete.
Fuel volatility adds to the margin pressure, but fuel is a problem every carrier faces. The difference is that Transat has no buffer. A mid-sized airline with a fragile balance sheet and a maintenance backlog it cannot control is operating inside a very narrow envelope. One more external shock and the acquisition conversations that have circulated for years become the only exit.
What the split says about recovery
The "mixed picture" language that appears in every economic update is doing real work here. Canada's economy in 2026 splits along several decoupling lines.
Discretionary retail that targets affordable luxury and social-occasion wear is finding buyers. Younger consumers are spending on clothes, beauty, and going-out categories even as they pull back on travel and durables. Younger consumers are reallocating toward lower-ticket dopamine--a $68 top, a coffee, an event--and away from high-commitment purchases that lock up savings or require financing.
Travel demand is high, but supply-side breakdowns in aircraft manufacturing and parts availability mean demand alone does not translate to profitability for smaller carriers. Transat faces an operational fragility problem in an industry where scale and balance-sheet depth have become survival requirements.
Grocery, for context, sits somewhere in between. Empire Co. grew sales and raised its dividend by 10.2% in 2026, but the sector faces sustained political pressure on pricing and margin. Success in grocery now means growing through discount banners like FreshCo and using loyalty programs like Scene+ as data tools to prevent store-switching. Growth comes through defensive moves: expanding discount counters, tightening margin controls, using member card data to watch which customers are switching to competitors.
The recovery is real for companies that found product-market fit in the current environment. It is not real for companies still structured for 2019.
Sources
Read Next
August Sales Fell 6.9%: What CREA's Numbers Actually Reveal About Buyer Hesitation
Canada's Resource Advantage: What Global Investors Are Betting On in 2026
Ohio Lost $4.8 Billion to Trump's Tariffs in 90 Days
How Much Identity Theft Coverage Your Family Needs, Based on Who's Actually at Risk