Fuel Hurts Air Canada, Copper Lifts Teck: 5 Checks for Your TSX Holdings
Air Canada lowered its outlook as fuel costs climbed. In the same stretch of earnings news, Teck reported a jump in profits on stronger copper and zinc prices. The same commodity cycle produced opposite results, and if you can tell which side of a price swing each of your holdings sits on, you stop mistaking a good quarter for a stronger business.
You've probably had this moment. You open two earnings updates, one company is trimming its forecast, another is reporting a better quarter, and you wonder whether your portfolio is benefiting from rising prices or quietly getting more exposed to them. Headlines tell you who had a good three months. They don't tell you whether one price move is helping one holding and hurting another. These five checks are a way to read the next earnings release you open. They aren't a reason to buy the miner or sell the airline.
Three checks that explain why a company's earnings changed
1. Name what the business buys and what it sells. An airline buys jet fuel. A miner sells metal. Many companies do both, so look for exposure on each side. Ask yourself which commodity shows up in costs and which shows up in revenue. You'll usually find the answer in the management's discussion and analysis (MD&A), the section where the company explains what drove its results. People skip this step because the headline names the sector and leaves out the input.
2. Separate price gains from real improvement. A profit jump can come from selling more, running cheaper, or simply getting a higher price for the same product. Only the first two say much about the business itself. Ask how much of the change came from selling prices, how much from volumes, how much from operating costs, and whether any one-time items are in the mix. Most releases break this down in the results discussion. A favourable market can make an ordinary quarter look like a turnaround.
3. Find out how much of a price swing actually reaches earnings. Some companies buy fuel ahead at a set price, which is called hedging. Others sign sales contracts or add surcharges that pass costs along. Ask what share of the exposure is covered, and for how long. Look in the risk and financial instruments notes. Keep in mind that this kind of protection is often partial and runs out on a fixed date.
Two checks that show what happens when prices turn around
4. Measure how much room the company has if prices reverse. A stronger quarter doesn't prove a company is resilient, and a weaker outlook doesn't prove it's fragile. To judge that, review three numbers: cash from operations, planned spending, and debt coming due. You'll find them in the cash flow statement and the liquidity section. If the plans only work at today's prices, the business depends on the market staying kind.
5. Add up your combined exposure. Put your direct holdings and your fund holdings side by side. A broad TSX fund already carries heavy weights in energy and materials. If you live in Alberta, your paycheque may also depend on energy activity, which ties your income to the same commodity cycle. Higher commodity prices can help what a company sells and hurt what it buys, so check both sides before you judge its earnings. Owning companies on opposite sides of a price doesn't guarantee they'll offset each other. In a broad sell-off, both shares can fall together.
A strong quarter is evidence to examine. It doesn't prove a holding is safer. Start small: open the latest earnings release for one company you own and find the commodity price change management says helped or hurt its results. Once you can name that one price, you'll know which way it pulls on your portfolio.


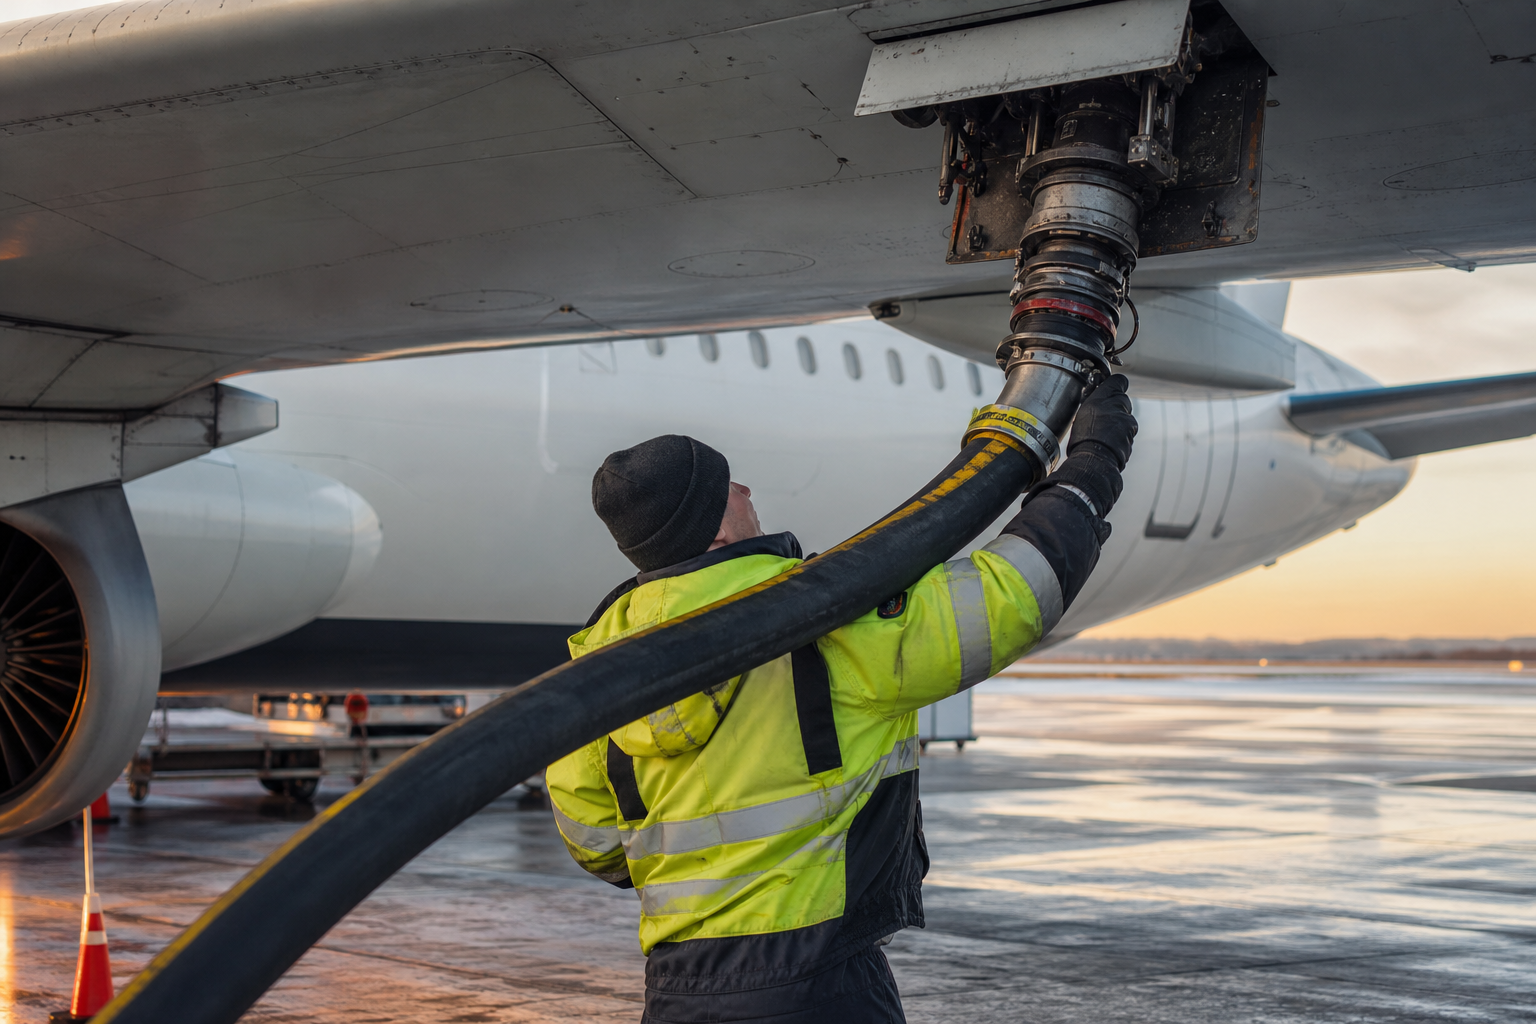

Air Canada lowered its outlook as fuel costs climbed. In the same stretch of earnings news, Teck reported a jump in profits on stronger copper and zinc prices. The same commodity cycle produced opposite results, and if you can tell which side of a price swing each of your holdings sits on, you stop mistaking a good quarter for a stronger business.
You've probably had this moment. You open two earnings updates, one company is trimming its forecast, another is reporting a better quarter, and you wonder whether your portfolio is benefiting from rising prices or quietly getting more exposed to them. Headlines tell you who had a good three months. They don't tell you whether one price move is helping one holding and hurting another. These five checks are a way to read the next earnings release you open. They aren't a reason to buy the miner or sell the airline.
Three checks that explain why a company's earnings changed
1. Name what the business buys and what it sells. An airline buys jet fuel. A miner sells metal. Many companies do both, so look for exposure on each side. Ask yourself which commodity shows up in costs and which shows up in revenue. You'll usually find the answer in the management's discussion and analysis (MD&A), the section where the company explains what drove its results. People skip this step because the headline names the sector and leaves out the input.
2. Separate price gains from real improvement. A profit jump can come from selling more, running cheaper, or simply getting a higher price for the same product. Only the first two say much about the business itself. Ask how much of the change came from selling prices, how much from volumes, how much from operating costs, and whether any one-time items are in the mix. Most releases break this down in the results discussion. A favourable market can make an ordinary quarter look like a turnaround.
3. Find out how much of a price swing actually reaches earnings. Some companies buy fuel ahead at a set price, which is called hedging. Others sign sales contracts or add surcharges that pass costs along. Ask what share of the exposure is covered, and for how long. Look in the risk and financial instruments notes. Keep in mind that this kind of protection is often partial and runs out on a fixed date.
Two checks that show what happens when prices turn around
4. Measure how much room the company has if prices reverse. A stronger quarter doesn't prove a company is resilient, and a weaker outlook doesn't prove it's fragile. To judge that, review three numbers: cash from operations, planned spending, and debt coming due. You'll find them in the cash flow statement and the liquidity section. If the plans only work at today's prices, the business depends on the market staying kind.
5. Add up your combined exposure. Put your direct holdings and your fund holdings side by side. A broad TSX fund already carries heavy weights in energy and materials. If you live in Alberta, your paycheque may also depend on energy activity, which ties your income to the same commodity cycle. Higher commodity prices can help what a company sells and hurt what it buys, so check both sides before you judge its earnings. Owning companies on opposite sides of a price doesn't guarantee they'll offset each other. In a broad sell-off, both shares can fall together.
A strong quarter is evidence to examine. It doesn't prove a holding is safer. Start small: open the latest earnings release for one company you own and find the commodity price change management says helped or hurt its results. Once you can name that one price, you'll know which way it pulls on your portfolio.
Read Next
Five Money Checks Canadian Snowbirds Should Finish Before Heading South
Canadian Bank Security Assumes a Human Is Logging In. AI Agents Break That
Before Storm Winds Arrive, Turn 5 Yard Hazards Into Protective Buffers
A 25 Basis Point Hike Doesn't Erase Variable's Long-Run Edge Over Fixed