Every Dollar Into an Index Fund Buys More of What Already Rose
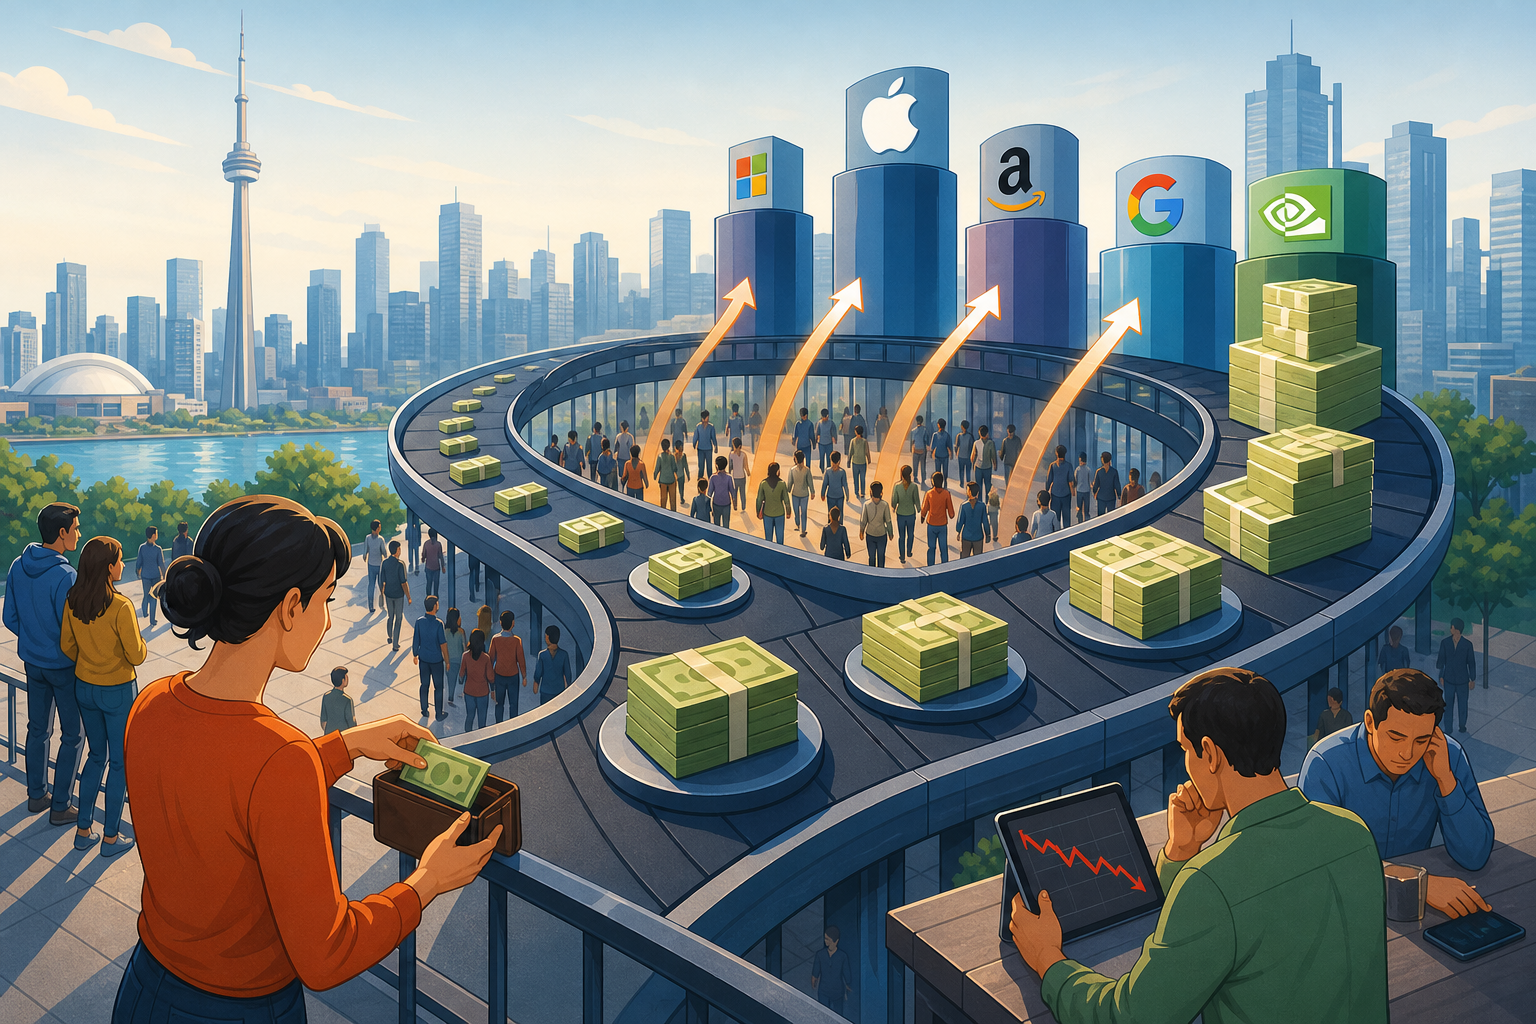
Put $1,000 into a broad Canadian index fund this week and the biggest companies in it take the largest slice before anyone has asked whether they're worth the price. The fund has no opinion. It buys every stock in proportion to its size, and size is just share price times shares outstanding.
That rule quietly changes what you own. Index funds and ETFs now hold a huge share of invested money, and in the U.S. passive funds recently passed active ones in total assets. On many trading days, most of the buying and selling comes from funds tracking an index, with no one studying the company behind the ticker. If your TFSA holds XIC or VCN, you're part of that flow. The stakes for you are simple: the more money moves this way, the more a stock's price reflects where money is going and the less it reflects what the business earns. Knowing how that loop works tells you what you actually hold and when to act.
Why an index fund's next dollar follows last year's winners
Here's an illustrative example. Say one company makes up 6% of an index. Of your $1,000, $60 goes to it. Now its shares climb faster than the rest and it grows to 8% of the index. Your next $1,000 sends it $80. Nothing about the business has to improve for that to happen. The price rose, so the weight rose, so the buying rose, which helps the price rise again.
That's the momentum loop. It rewards size, and it explains why the top ten companies in major indices now make up an unusually large share of their total value. In Canada the pattern has a local flavour: the big banks and major energy producers dominate the TSX 60, so passive money flowing into Canadian equity ETFs lands heavily on them. For an Edmonton investor whose paycheque, business or home value already rides on oil and lending, the "diversified" fund can double down on the same bet.
What happens when the buying slows or reverses
The loop runs in both directions. When people sell index funds, the funds must sell every holding in proportion, and the largest names get hit with the most selling. Critics worry that in a sharp downturn there could be too few active buyers left to set a floor, so prices fall further than the businesses deserve before someone steps in.
Two honest counterweights belong here. Index funds have slashed the cost of investing, with fees far below the old mutual fund model, and that saving compounds for decades. Markets have also corrected when prices drifted too far from reality. Those corrections tend to arrive suddenly, though, and they land hardest on whatever the loop had inflated most.
Three checks for a portfolio built on index funds
You don't need to abandon index funds to handle this. You need to see the loop and put a few rules around it.
Add up your real exposure. Look up the top ten holdings and sector weights of each fund you own, then combine them across your TFSA, RRSP and any taxable account. Count your job and your home too. If banks and energy show up everywhere, you know where your risk sits.
Set target weights and rebalance on a schedule. Pick the mix you want and trim back when something drifts well past it. Do the selling inside a TFSA or RRSP where possible, since in a taxable account half of a capital gain is added to your income.
Look where the automatic money doesn't go. Smaller and mid-sized companies outside the big indices get little passive buying, which can leave some of them priced below what their earnings justify. The same discipline applies there: a low price still has to be backed by a business that makes money.
An index fund will always buy more of whatever already rose. Your job is to decide how much of that you actually want.



Put $1,000 into a broad Canadian index fund this week and the biggest companies in it take the largest slice before anyone has asked whether they're worth the price. The fund has no opinion. It buys every stock in proportion to its size, and size is just share price times shares outstanding.
That rule quietly changes what you own. Index funds and ETFs now hold a huge share of invested money, and in the U.S. passive funds recently passed active ones in total assets. On many trading days, most of the buying and selling comes from funds tracking an index, with no one studying the company behind the ticker. If your TFSA holds XIC or VCN, you're part of that flow. The stakes for you are simple: the more money moves this way, the more a stock's price reflects where money is going and the less it reflects what the business earns. Knowing how that loop works tells you what you actually hold and when to act.
Why an index fund's next dollar follows last year's winners
Here's an illustrative example. Say one company makes up 6% of an index. Of your $1,000, $60 goes to it. Now its shares climb faster than the rest and it grows to 8% of the index. Your next $1,000 sends it $80. Nothing about the business has to improve for that to happen. The price rose, so the weight rose, so the buying rose, which helps the price rise again.
That's the momentum loop. It rewards size, and it explains why the top ten companies in major indices now make up an unusually large share of their total value. In Canada the pattern has a local flavour: the big banks and major energy producers dominate the TSX 60, so passive money flowing into Canadian equity ETFs lands heavily on them. For an Edmonton investor whose paycheque, business or home value already rides on oil and lending, the "diversified" fund can double down on the same bet.
What happens when the buying slows or reverses
The loop runs in both directions. When people sell index funds, the funds must sell every holding in proportion, and the largest names get hit with the most selling. Critics worry that in a sharp downturn there could be too few active buyers left to set a floor, so prices fall further than the businesses deserve before someone steps in.
Two honest counterweights belong here. Index funds have slashed the cost of investing, with fees far below the old mutual fund model, and that saving compounds for decades. Markets have also corrected when prices drifted too far from reality. Those corrections tend to arrive suddenly, though, and they land hardest on whatever the loop had inflated most.
Three checks for a portfolio built on index funds
You don't need to abandon index funds to handle this. You need to see the loop and put a few rules around it.
An index fund will always buy more of whatever already rose. Your job is to decide how much of that you actually want.
Read Next
Five Money Checks Canadian Snowbirds Should Finish Before Heading South
Canadian Bank Security Assumes a Human Is Logging In. AI Agents Break That
Before Storm Winds Arrive, Turn 5 Yard Hazards Into Protective Buffers
A 25 Basis Point Hike Doesn't Erase Variable's Long-Run Edge Over Fixed