Why One in Four Working Canadians Run Out of Money Every Month
A $120,000-a-year civil engineer in Edmonton defaulted on her Visa payment in July 2026. Not because she lost her job. Because her mortgage renewed at 5.9%, her car loan hit $780 a month, and her line of credit carried a balance she'd been rolling over since groceries spiked in late 2022. The number at the end of the month was negative.
She isn't what most people picture when they hear "financial fragility," but she fits the pattern exactly. The National Payroll Institute's 2024-2025 survey found that roughly one in four working Canadians would be unable to meet their financial obligations if their paycheque arrived even one week late. The thread connecting them is the gap between what they earn and what they owe.
The double squeeze that collapsed the margin
Two forces converged to erase the buffer most households used to carry. Interest rates climbed from near-zero in 2021 to over 5% by mid-2023, which meant anyone renewing a mortgage or carrying variable-rate debt saw their servicing costs jump. A $400,000 mortgage that cost $1,680 a month at 2.5% became $2,340 at 5.5%. That's an extra $660 leaving the account before groceries, utilities, or the truck payment.
At the same time, the cost of essentials levelled off at a plateau 15-20% higher than pre-pandemic. Inflation cooled from its 2022-2023 peak, but prices did not fall. A household spending $800 a month on groceries in 2021 now spends $950 for the same items. Multiply that across rent, gas, insurance, and utilities, and the cumulative bite is several hundred dollars a month, money that used to sit in the account as slack.
For Albertans, the traditional advantage of lower housing costs has started to erode. Edmonton remains more affordable than Calgary, but rapid population growth has tightened the rental market and pushed entry-level home prices higher. Property tax hikes and utility cost increases added new pressure to monthly budgets just as mortgage renewals began hitting in earnest.
The debt cycle that replaced savings
Statistics Canada reported in mid-2026 that Canadians owed roughly $1.76 in credit market debt for every dollar of disposable income. That ratio doesn't move unless the numerator or denominator shifts, and with wage growth lagging cumulative cost increases in most sectors, the only direction it has gone is up.
What happened in practice is that households used credit cards to cover the gap between income and expenses. A $300 shortfall one month became a $350 balance the next, compounding at 19.99%. High-interest debt makes it harder to save for a down payment, harder to build an emergency fund, and harder to withstand a single missed paycheque. The recommended emergency reserve is three to six months of living expenses. Most Canadians currently hold less than one.
The lag effect from the Bank of Canada's late-2024 easing cycle means many Albertans are only now feeling the full impact on their lines of credit and variable-rate loans. Rates have started to come down, but the damage from two years of elevated servicing costs is already baked into the balance sheets.
What "paycheque to paycheque" actually measures
Living paycheque to paycheque doesn't always signal a low income. Some survey respondents earning well into six figures fit the definition because they maxed out their lifestyle to match their gross pay. A household pulling in $180,000 that committed to a $950,000 mortgage, two leased vehicles, and private school tuition has the same cash-flow fragility as a household earning $60,000 with $1,200 in rent and $8,000 in credit card debt.
The distinction matters for anyone trying to understand the rental market or the demand side of housing. The 28% figure represents a growing pool of people who cannot save for a down payment because every dollar is spoken for before it arrives. They stay renters longer because the math leaves them no other choice.
For first-time buyers in Edmonton, the implication is tactical: buy below your maximum mortgage qualification. Payment stability beats square footage when a missed paycheque isn't theoretical anymore.


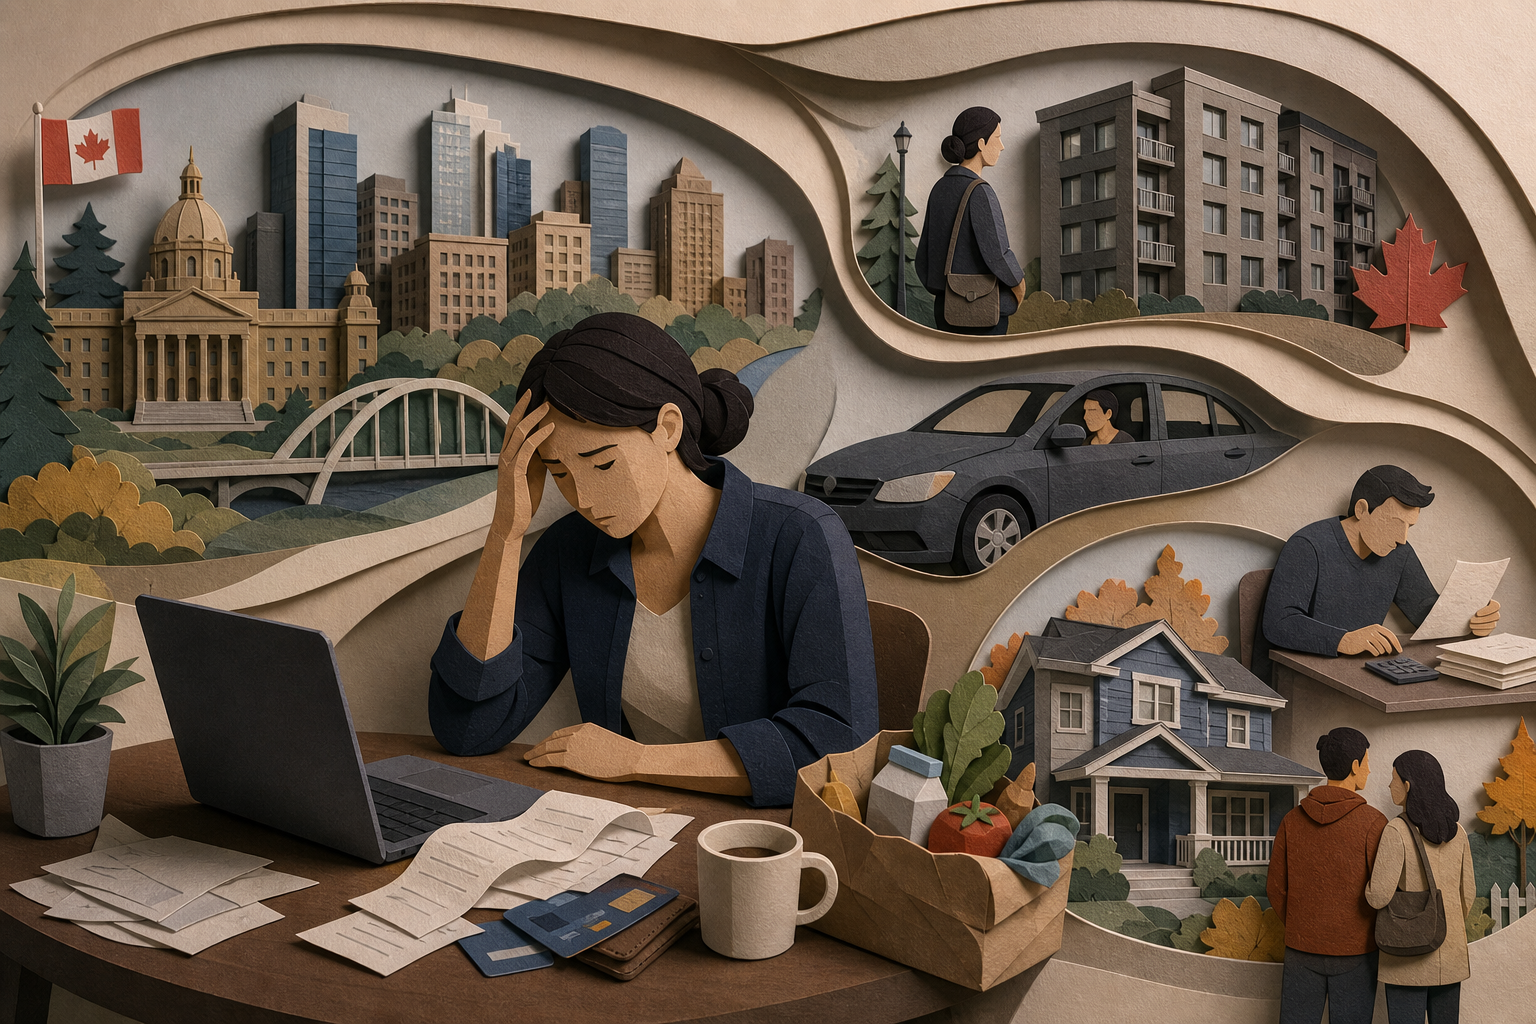

A $120,000-a-year civil engineer in Edmonton defaulted on her Visa payment in July 2026. Not because she lost her job. Because her mortgage renewed at 5.9%, her car loan hit $780 a month, and her line of credit carried a balance she'd been rolling over since groceries spiked in late 2022. The number at the end of the month was negative.
She isn't what most people picture when they hear "financial fragility," but she fits the pattern exactly. The National Payroll Institute's 2024-2025 survey found that roughly one in four working Canadians would be unable to meet their financial obligations if their paycheque arrived even one week late. The thread connecting them is the gap between what they earn and what they owe.
The double squeeze that collapsed the margin
Two forces converged to erase the buffer most households used to carry. Interest rates climbed from near-zero in 2021 to over 5% by mid-2023, which meant anyone renewing a mortgage or carrying variable-rate debt saw their servicing costs jump. A $400,000 mortgage that cost $1,680 a month at 2.5% became $2,340 at 5.5%. That's an extra $660 leaving the account before groceries, utilities, or the truck payment.
At the same time, the cost of essentials levelled off at a plateau 15-20% higher than pre-pandemic. Inflation cooled from its 2022-2023 peak, but prices did not fall. A household spending $800 a month on groceries in 2021 now spends $950 for the same items. Multiply that across rent, gas, insurance, and utilities, and the cumulative bite is several hundred dollars a month, money that used to sit in the account as slack.
For Albertans, the traditional advantage of lower housing costs has started to erode. Edmonton remains more affordable than Calgary, but rapid population growth has tightened the rental market and pushed entry-level home prices higher. Property tax hikes and utility cost increases added new pressure to monthly budgets just as mortgage renewals began hitting in earnest.
The debt cycle that replaced savings
Statistics Canada reported in mid-2026 that Canadians owed roughly $1.76 in credit market debt for every dollar of disposable income. That ratio doesn't move unless the numerator or denominator shifts, and with wage growth lagging cumulative cost increases in most sectors, the only direction it has gone is up.
What happened in practice is that households used credit cards to cover the gap between income and expenses. A $300 shortfall one month became a $350 balance the next, compounding at 19.99%. High-interest debt makes it harder to save for a down payment, harder to build an emergency fund, and harder to withstand a single missed paycheque. The recommended emergency reserve is three to six months of living expenses. Most Canadians currently hold less than one.
The lag effect from the Bank of Canada's late-2024 easing cycle means many Albertans are only now feeling the full impact on their lines of credit and variable-rate loans. Rates have started to come down, but the damage from two years of elevated servicing costs is already baked into the balance sheets.
What "paycheque to paycheque" actually measures
Living paycheque to paycheque doesn't always signal a low income. Some survey respondents earning well into six figures fit the definition because they maxed out their lifestyle to match their gross pay. A household pulling in $180,000 that committed to a $950,000 mortgage, two leased vehicles, and private school tuition has the same cash-flow fragility as a household earning $60,000 with $1,200 in rent and $8,000 in credit card debt.
The distinction matters for anyone trying to understand the rental market or the demand side of housing. The 28% figure represents a growing pool of people who cannot save for a down payment because every dollar is spoken for before it arrives. They stay renters longer because the math leaves them no other choice.
For first-time buyers in Edmonton, the implication is tactical: buy below your maximum mortgage qualification. Payment stability beats square footage when a missed paycheque isn't theoretical anymore.
Sources
Read Next
In Nearly All 50 Major U.S. Cities, Minimum Wage No Longer Covers a One-Bedroom Apartment
Builders Can't Finance Tiny Homes Fast Enough to Meet Canadian Demand
5 Identity Theft Threats Coming in 2026 and What to Do Now
Can $1.16 Million Actually Retire You at 63? The Two Numbers Tom Missed