Who Really Gains When Canada's Banks and Telecoms Join Forces Against Fraud?
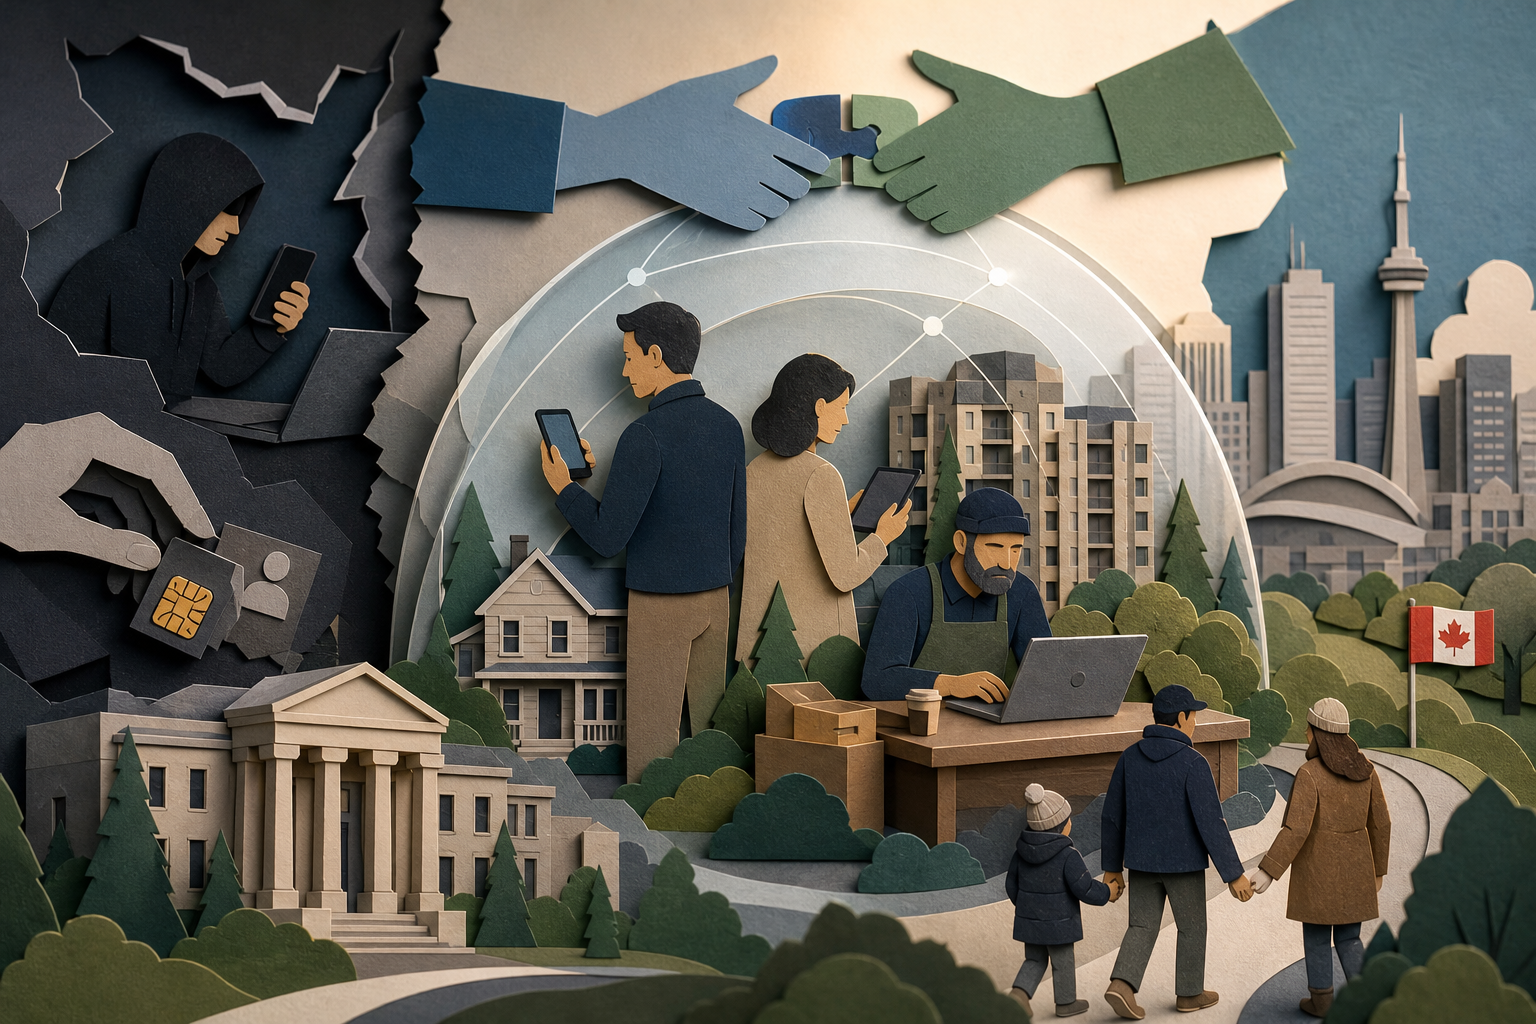
When a fraudster steals your phone number, your carrier sees a routine account change and your bank sees a customer logging in correctly. Neither alarm goes off, because each company only ever saw half of the attack. That blind spot is what Canada's Big Five banks (RBC, TD, Scotiabank, BMO and CIBC) and the major telecom providers say their new shared fraud platform will close, by passing warning signs between them as they happen.
It's worth asking who that protects. The honest answer is both you and them, and the overlap is narrower than the headlines suggest. The platform targets the fraud that lands on the bank's and carrier's own books. The fraud where you authorize the payment yourself still lands on yours. If you're saving a down payment, holding money for a purchase or managing a rental portfolio, that difference decides where your own guard needs to be.
A safeguard tends to protect whoever pays for the loss
The main target is SIM swapping and unauthorized number porting. A criminal persuades a carrier to move your number to a phone they control, then receives the one-time codes your bank texts you. Once that's done, the security step meant to stop them becomes the step that lets them in.
When that happens, the bank and the carrier are exposed. They face disputes, reimbursements, complaints and regulators. Sharing data to catch it cuts their costs and helps customers, which is a fair trade. Some consumer advocates have raised a reasonable worry about how much information private companies now pass between themselves, and the founding names are the largest players in both industries. A shared fraud network that only the biggest institutions run gives them one more thing smaller rivals have to match. That can be good security and good strategy at once.
What the platform can't do is stop you from sending money to someone who has fooled you. A fake investment pitch, a romance scam or an urgent e-transfer request from a voice that sounds like family all look like a legitimate customer acting freely. The Canadian Anti-Fraud Centre counted $554 million in reported losses in 2023, with investment scams and phishing near the top. Scams cloned with AI voices and polished emails make the old "I'd know it if I saw it" instinct much less reliable than it used to be.
Your phone number now works like a key to your money
For many Albertans, the text code is the lock on their savings. Anyone holding your number can often reset your banking password. That makes your mobile account as important as your bank PIN, and most people protect it far less.
A few steps close most of the gap. Call your carrier and add a PIN or password to your account, and ask what it requires before your number can be moved. Where your bank or brokerage offers an authenticator app instead of text codes, use it. Business owners who run personal and business banking through one phone number should know a single swap reaches both.
Expect a bit more friction, too. Extra checks when you change your phone plan or move a large sum are the system working, so give them a minute instead of a sigh.
The riskiest moment is when large sums are moving
Fraud hits hardest when large sums move, and in real estate that's the weeks around a closing. Your down payment sits in one account and needs to reach a lawyer's trust account by a set date. A spoofed email with "updated wiring instructions" lands at exactly that moment, and you'd be the one authorizing the payment. Once money leaves through Canada's faster payment systems, getting it back in Alberta can take months or years, if it comes back at all.
Before you send anything for a purchase, confirm payment details by phoning your lawyer at a number you already have, never one in the email.
When you hear about a new fraud protection, ask who loses money if it fails. If the answer is the bank, it'll probably be done well. If the answer is you, that one is still your job.
Canadian Anti-Fraud Centre - In 2023, the Canadian Anti-Fraud Centre (CAFC) processed 62,365 fraud reports involving over $554 million in reported losses - 2024-01-15. https://x.com/canantifraud/status/1747656665334165965

When a fraudster steals your phone number, your carrier sees a routine account change and your bank sees a customer logging in correctly. Neither alarm goes off, because each company only ever saw half of the attack. That blind spot is what Canada's Big Five banks (RBC, TD, Scotiabank, BMO and CIBC) and the major telecom providers say their new shared fraud platform will close, by passing warning signs between them as they happen.
It's worth asking who that protects. The honest answer is both you and them, and the overlap is narrower than the headlines suggest. The platform targets the fraud that lands on the bank's and carrier's own books. The fraud where you authorize the payment yourself still lands on yours. If you're saving a down payment, holding money for a purchase or managing a rental portfolio, that difference decides where your own guard needs to be.
A safeguard tends to protect whoever pays for the loss
The main target is SIM swapping and unauthorized number porting. A criminal persuades a carrier to move your number to a phone they control, then receives the one-time codes your bank texts you. Once that's done, the security step meant to stop them becomes the step that lets them in.
When that happens, the bank and the carrier are exposed. They face disputes, reimbursements, complaints and regulators. Sharing data to catch it cuts their costs and helps customers, which is a fair trade. Some consumer advocates have raised a reasonable worry about how much information private companies now pass between themselves, and the founding names are the largest players in both industries. A shared fraud network that only the biggest institutions run gives them one more thing smaller rivals have to match. That can be good security and good strategy at once.
What the platform can't do is stop you from sending money to someone who has fooled you. A fake investment pitch, a romance scam or an urgent e-transfer request from a voice that sounds like family all look like a legitimate customer acting freely. The Canadian Anti-Fraud Centre counted $554 million in reported losses in 2023, with investment scams and phishing near the top. Scams cloned with AI voices and polished emails make the old "I'd know it if I saw it" instinct much less reliable than it used to be.
Your phone number now works like a key to your money
For many Albertans, the text code is the lock on their savings. Anyone holding your number can often reset your banking password. That makes your mobile account as important as your bank PIN, and most people protect it far less.
A few steps close most of the gap. Call your carrier and add a PIN or password to your account, and ask what it requires before your number can be moved. Where your bank or brokerage offers an authenticator app instead of text codes, use it. Business owners who run personal and business banking through one phone number should know a single swap reaches both.
Expect a bit more friction, too. Extra checks when you change your phone plan or move a large sum are the system working, so give them a minute instead of a sigh.
The riskiest moment is when large sums are moving
Fraud hits hardest when large sums move, and in real estate that's the weeks around a closing. Your down payment sits in one account and needs to reach a lawyer's trust account by a set date. A spoofed email with "updated wiring instructions" lands at exactly that moment, and you'd be the one authorizing the payment. Once money leaves through Canada's faster payment systems, getting it back in Alberta can take months or years, if it comes back at all.
Before you send anything for a purchase, confirm payment details by phoning your lawyer at a number you already have, never one in the email.
When you hear about a new fraud protection, ask who loses money if it fails. If the answer is the bank, it'll probably be done well. If the answer is you, that one is still your job.
Sources
Read Next
AI Stocks Are Priced for Productivity Gains That Haven't Arrived Yet
The AI Trade Was Priced for Endless Demand. Memory Chips Disagree.
What Fairfax Financial's India Deal Must Deliver to Justify Nearly 32% Upside
Why the TSX's Leading Sectors Look So Different From the U.S. Market's