AI Stocks Are Priced for Productivity Gains That Haven't Arrived Yet
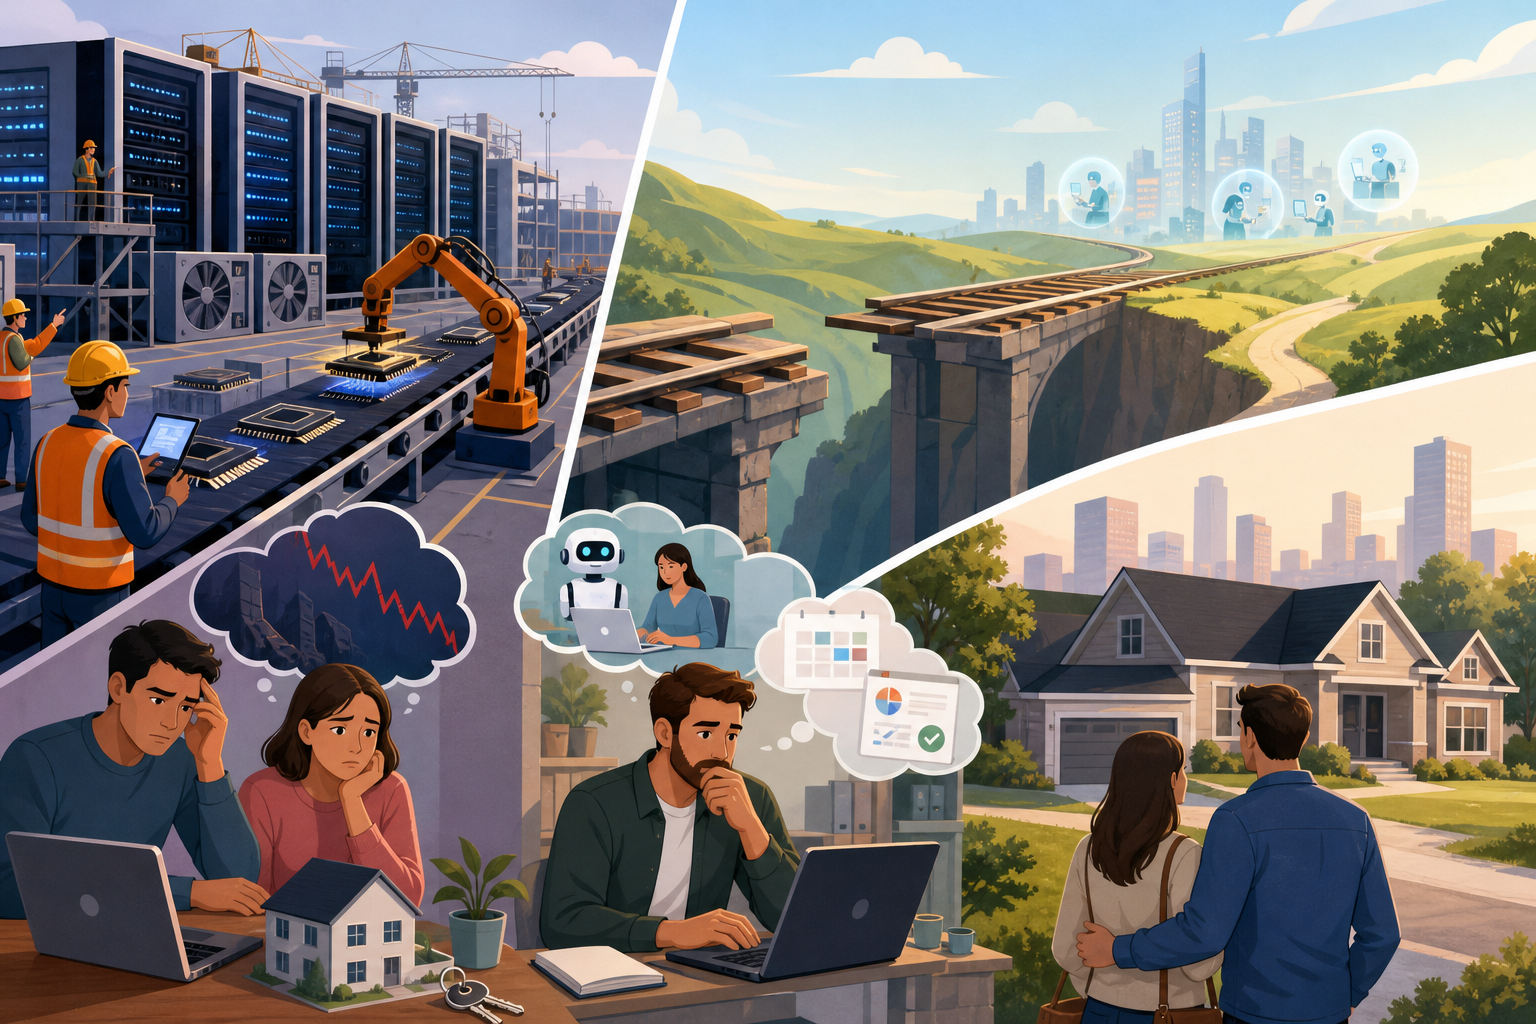
Across 2024 and 2025, the biggest tech companies committed more than $200 billion to AI chips and data centres, according to their own filings. That money is spent. What it was meant to buy is a broad jump in how much work people and businesses get done, and that jump hasn't shown up in the national numbers yet. The Bank of Canada still describes weak productivity as a long-running problem for the Canadian economy, and most small and mid-sized Canadian firms are only starting to try AI tools.
Stock prices for those companies assume the payoff arrives on time. If the bills keep arriving faster than the revenue, prices reset. So many portfolios now lean on a handful of these firms that the reset would reach plenty of people who never meant to bet on AI. Whether that matters to you comes down to one thing: whether you need the money on a date.
A broad index can still be a narrow bet
The standard advice is to buy the whole market and hold it. Over long stretches that advice has served people well, and it still does. Low fees and no stock picking are hard to beat.
The catch is in how an index is built. Big companies get big weights. In 2024 and 2025, the top 10 stocks in the S&P 500 made up more than 30% of the index's total value, and many of those names are the same firms pouring money into AI. Someone in Edmonton holding a popular US index ETF in an RRSP or TFSA may think they own 500 companies. In practice, close to a third of their money rides on a few.
Look at the fund's top holdings by weight, not the name on the label. That one page tells you more about your risk than the fund's description does.
Being right about AI and making money on AI stocks run on different clocks
New technology tends to get built before it gets used well. In the late 1990s, companies laid huge amounts of fibre-optic cable. Many of them collapsed, and the internet still went on to change everything, years later, on cable that had been bought cheap out of bankruptcy. Electricity and the internet each took decades to show up clearly in productivity statistics.
AI may follow the same slow path. A drop in AI stocks wouldn't mean the technology failed. It would mean the price got ahead of the payoff. Some companies that have little to do with AI, in areas like cybersecurity, could get dragged down with the rest simply because they sit in the same funds. You can be completely right about where AI is heading and still lose money if you paid for that future too early.
Your own deadline is the risk that matters
If you won't touch the money for 20 years, a reset is unpleasant but survivable. Things change when the money has a job to do soon.
Here's an illustration with round numbers. Say you've built $120,000 toward a down payment on a move-up home in Sherwood Park, held in a fund where a third of the value sits in the biggest tech names. If those names fall 30% and everything else stays flat, the fund drops about 10%. That's $12,000 gone from your down payment, possibly a few months before you need to write the cheque.
Dates show up in other places too. Some lending and investment products are built around asset levels, like the accredited investor threshold of $1,000,000 in financial assets, not counting your principal residence. A sharp drop can push a portfolio under a line you were counting on. On the flip side, selling a winner early to protect a down payment has a cost as well: under CRA rules, 50% of the capital gain is taxable on the first $250,000. Plan that sale ahead of time and don't let a bad month make the call for you.
Before deciding how much AI risk you can carry, put a date beside each pot of money. Money with a date in the next few years belongs somewhere that doesn't depend on a quarterly earnings call. Money with no date can afford to wait for the payoff to catch up with the price.

Across 2024 and 2025, the biggest tech companies committed more than $200 billion to AI chips and data centres, according to their own filings. That money is spent. What it was meant to buy is a broad jump in how much work people and businesses get done, and that jump hasn't shown up in the national numbers yet. The Bank of Canada still describes weak productivity as a long-running problem for the Canadian economy, and most small and mid-sized Canadian firms are only starting to try AI tools.
Stock prices for those companies assume the payoff arrives on time. If the bills keep arriving faster than the revenue, prices reset. So many portfolios now lean on a handful of these firms that the reset would reach plenty of people who never meant to bet on AI. Whether that matters to you comes down to one thing: whether you need the money on a date.
A broad index can still be a narrow bet
The standard advice is to buy the whole market and hold it. Over long stretches that advice has served people well, and it still does. Low fees and no stock picking are hard to beat.
The catch is in how an index is built. Big companies get big weights. In 2024 and 2025, the top 10 stocks in the S&P 500 made up more than 30% of the index's total value, and many of those names are the same firms pouring money into AI. Someone in Edmonton holding a popular US index ETF in an RRSP or TFSA may think they own 500 companies. In practice, close to a third of their money rides on a few.
Look at the fund's top holdings by weight, not the name on the label. That one page tells you more about your risk than the fund's description does.
Being right about AI and making money on AI stocks run on different clocks
New technology tends to get built before it gets used well. In the late 1990s, companies laid huge amounts of fibre-optic cable. Many of them collapsed, and the internet still went on to change everything, years later, on cable that had been bought cheap out of bankruptcy. Electricity and the internet each took decades to show up clearly in productivity statistics.
AI may follow the same slow path. A drop in AI stocks wouldn't mean the technology failed. It would mean the price got ahead of the payoff. Some companies that have little to do with AI, in areas like cybersecurity, could get dragged down with the rest simply because they sit in the same funds. You can be completely right about where AI is heading and still lose money if you paid for that future too early.
Your own deadline is the risk that matters
If you won't touch the money for 20 years, a reset is unpleasant but survivable. Things change when the money has a job to do soon.
Here's an illustration with round numbers. Say you've built $120,000 toward a down payment on a move-up home in Sherwood Park, held in a fund where a third of the value sits in the biggest tech names. If those names fall 30% and everything else stays flat, the fund drops about 10%. That's $12,000 gone from your down payment, possibly a few months before you need to write the cheque.
Dates show up in other places too. Some lending and investment products are built around asset levels, like the accredited investor threshold of $1,000,000 in financial assets, not counting your principal residence. A sharp drop can push a portfolio under a line you were counting on. On the flip side, selling a winner early to protect a down payment has a cost as well: under CRA rules, 50% of the capital gain is taxable on the first $250,000. Plan that sale ahead of time and don't let a bad month make the call for you.
Before deciding how much AI risk you can carry, put a date beside each pot of money. Money with a date in the next few years belongs somewhere that doesn't depend on a quarterly earnings call. Money with no date can afford to wait for the payoff to catch up with the price.
Read Next
The AI Trade Was Priced for Endless Demand. Memory Chips Disagree.
What Fairfax Financial's India Deal Must Deliver to Justify Nearly 32% Upside
Why the TSX's Leading Sectors Look So Different From the U.S. Market's
Who Really Gains When Canada's Banks and Telecoms Join Forces Against Fraud?