Wealthsimple Predict Creates Insider Trading Grey Zones Securities Law Never Contemplated
A parliamentary staffer who knows the federal budget contains a surprise carbon tax rebate can now, from their phone at lunch, bet $500 that the rebate will be announced. If they're right, they pocket $500. If they're wrong, they lose what they wagered. No regulator flags it.
This is not a hypothetical. It is the structure Wealthsimple Predict was approved to launch with in 2026, and securities law has no clear mechanism to stop it.
Traditional insider trading rules were written for equities. An insider is someone with a fiduciary duty to a company who trades on material non-public information. The law assumes the information relates to a security, shares, bonds, derivatives tied to a corporate entity. Prediction markets do not fit that template. The contracts settle on events: central bank decisions, election outcomes, whether a film crosses $100 million at the box office. The person holding non-public information about the event is not always an insider to a corporation. Often, they are a government employee, a campaign volunteer, a studio executive, or a journalist.
The Incentive Structure Changed
Before mainstream prediction platforms, monetizing early knowledge of a policy shift required setting up offshore accounts, finding counterparties, and moving money in ways that left trails. Friction acted as a deterrent. Wealthsimple Predict removed the friction. The app integrates event-based contracts into the same interface Canadians already use for index funds and savings accounts. A contract priced at $0.68 means the market assigns a 68% probability to the event. If you know it is closer to 95%, you buy at $0.68 and sell at $1.00 when it resolves.
The profit is not hypothetical. It is guaranteed, provided the information is accurate. A policy adviser who knows a rate cut is coming does not need to short a bank stock and hope the market reacts as expected. They can trade directly on the binary outcome. The payout structure is simpler, the holding period shorter, and the detection risk lower.
What Enforcement Looks Like Now
The Canadian Investment Regulatory Organization and the Canadian Securities Administrators have jurisdiction over securities and certain derivatives. Event contracts sit in between. Provincial gaming regulators treat them as skill-based prediction rather than chance-based gambling, which exempts them from most gaming restrictions. Securities regulators have not yet clarified whether a contract on a federal budget decision constitutes a security.
This creates enforcement gaps. If a deputy minister's assistant bets heavily on an infrastructure announcement they helped draft, which regulator investigates? The trade does not involve a company. It does not involve a traditional derivative. The information asymmetry is real, but the legal framework to prosecute it is ambiguous.
In the United States, the Commodity Futures Trading Commission blocked Kalshi from listing certain election contracts in September 2023, arguing they posed integrity risks. The decision was later reversed in court in 2024, and the CFTC dropped its appeal in May 2025. The legal fight clarified the regulatory boundary. Canada has not had that fight yet.
Why This Matters Beyond Individual Trades
Prediction markets are often defended as information aggregation tools. The claim is that they surface the "wisdom of crowds" and produce more accurate forecasts than polls or pundits. That argument collapses when the crowd includes participants with asymmetric access to the outcome. A market is not discovering information when a government staffer is feeding it the answer.
The broader risk is distortion. If political operatives or corporate insiders can move prediction market prices with early access, those prices stop being forecasts and become instruments for shaping perception. A candidate who looks 20 points more likely to win than they actually are can attract donors, volunteers, and media coverage as if the market's assessment were neutral.
Wealthsimple's platform limits individual contract losses to the amount paid for each contract, and users can only trade with funds already deposited (no margin or leverage is permitted under Canadian regulations). But such limits do not prevent coordination. Multiple people with early knowledge can move a thinly traded market.
Securities law will eventually catch up. It always does. But the gap between the innovation arriving and the law adapting is where the damage happens.


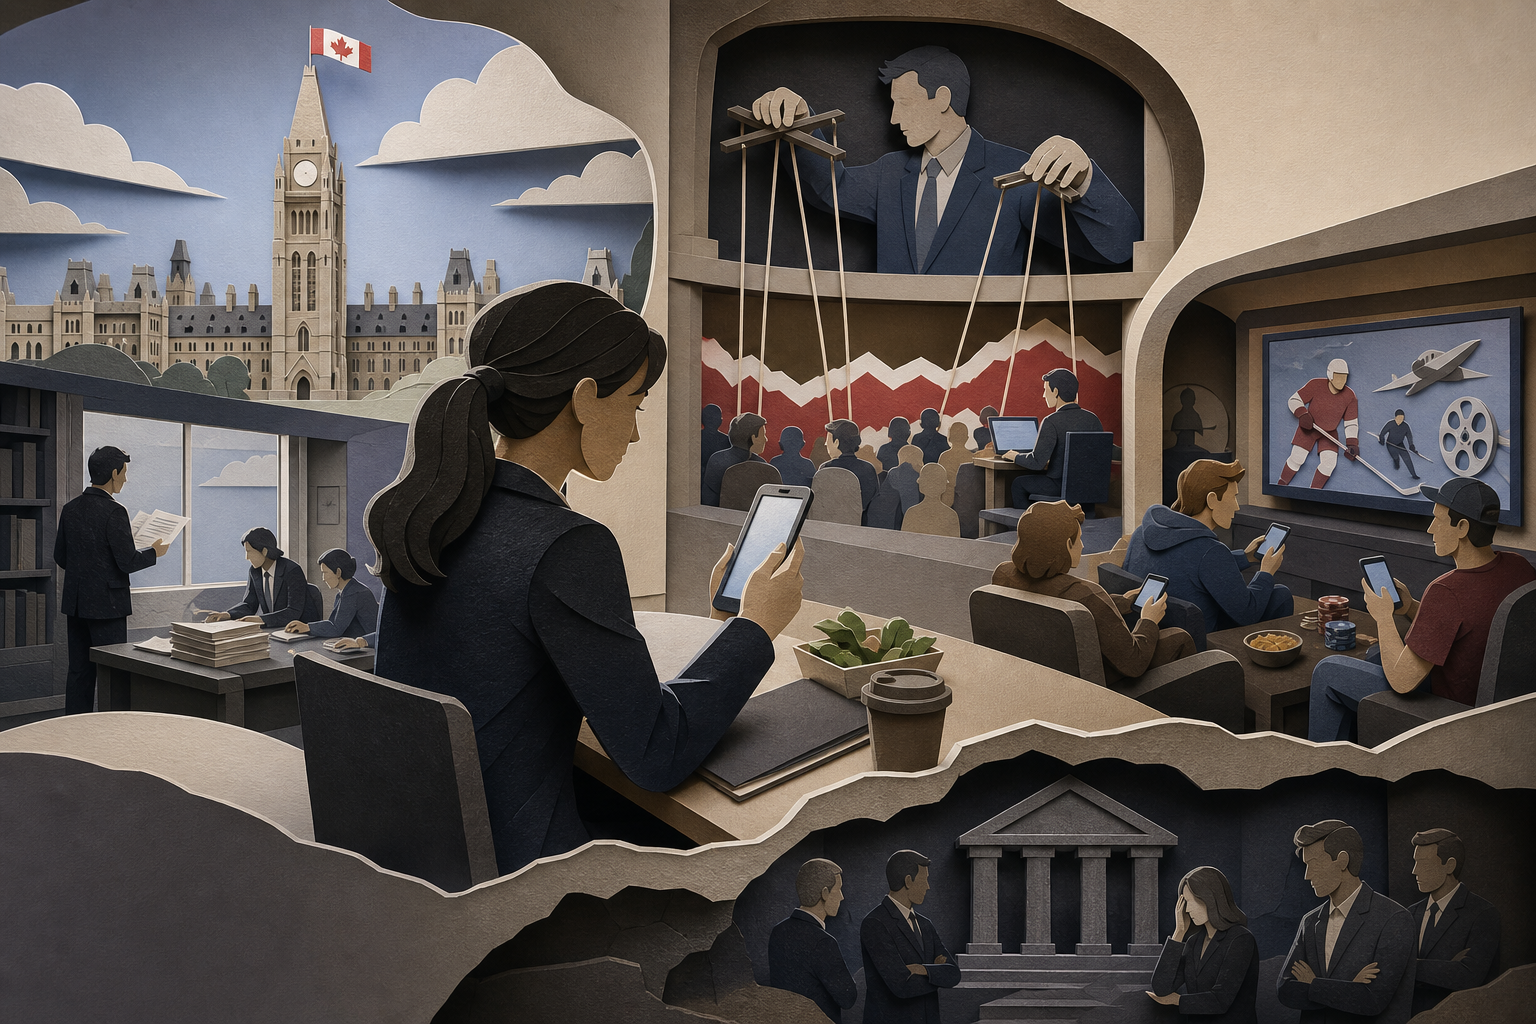

A parliamentary staffer who knows the federal budget contains a surprise carbon tax rebate can now, from their phone at lunch, bet $500 that the rebate will be announced. If they're right, they pocket $500. If they're wrong, they lose what they wagered. No regulator flags it.
This is not a hypothetical. It is the structure Wealthsimple Predict was approved to launch with in 2026, and securities law has no clear mechanism to stop it.
Traditional insider trading rules were written for equities. An insider is someone with a fiduciary duty to a company who trades on material non-public information. The law assumes the information relates to a security, shares, bonds, derivatives tied to a corporate entity. Prediction markets do not fit that template. The contracts settle on events: central bank decisions, election outcomes, whether a film crosses $100 million at the box office. The person holding non-public information about the event is not always an insider to a corporation. Often, they are a government employee, a campaign volunteer, a studio executive, or a journalist.
The Incentive Structure Changed
Before mainstream prediction platforms, monetizing early knowledge of a policy shift required setting up offshore accounts, finding counterparties, and moving money in ways that left trails. Friction acted as a deterrent. Wealthsimple Predict removed the friction. The app integrates event-based contracts into the same interface Canadians already use for index funds and savings accounts. A contract priced at $0.68 means the market assigns a 68% probability to the event. If you know it is closer to 95%, you buy at $0.68 and sell at $1.00 when it resolves.
The profit is not hypothetical. It is guaranteed, provided the information is accurate. A policy adviser who knows a rate cut is coming does not need to short a bank stock and hope the market reacts as expected. They can trade directly on the binary outcome. The payout structure is simpler, the holding period shorter, and the detection risk lower.
What Enforcement Looks Like Now
The Canadian Investment Regulatory Organization and the Canadian Securities Administrators have jurisdiction over securities and certain derivatives. Event contracts sit in between. Provincial gaming regulators treat them as skill-based prediction rather than chance-based gambling, which exempts them from most gaming restrictions. Securities regulators have not yet clarified whether a contract on a federal budget decision constitutes a security.
This creates enforcement gaps. If a deputy minister's assistant bets heavily on an infrastructure announcement they helped draft, which regulator investigates? The trade does not involve a company. It does not involve a traditional derivative. The information asymmetry is real, but the legal framework to prosecute it is ambiguous.
In the United States, the Commodity Futures Trading Commission blocked Kalshi from listing certain election contracts in September 2023, arguing they posed integrity risks. The decision was later reversed in court in 2024, and the CFTC dropped its appeal in May 2025. The legal fight clarified the regulatory boundary. Canada has not had that fight yet.
Why This Matters Beyond Individual Trades
Prediction markets are often defended as information aggregation tools. The claim is that they surface the "wisdom of crowds" and produce more accurate forecasts than polls or pundits. That argument collapses when the crowd includes participants with asymmetric access to the outcome. A market is not discovering information when a government staffer is feeding it the answer.
The broader risk is distortion. If political operatives or corporate insiders can move prediction market prices with early access, those prices stop being forecasts and become instruments for shaping perception. A candidate who looks 20 points more likely to win than they actually are can attract donors, volunteers, and media coverage as if the market's assessment were neutral.
Wealthsimple's platform limits individual contract losses to the amount paid for each contract, and users can only trade with funds already deposited (no margin or leverage is permitted under Canadian regulations). But such limits do not prevent coordination. Multiple people with early knowledge can move a thinly traded market.
Securities law will eventually catch up. It always does. But the gap between the innovation arriving and the law adapting is where the damage happens.
Sources
Read Next
GIC rates stall as bonds retreat: why deposit accounts still lag
Why Your Employer's Life Insurance Probably Covers Less Than You Think
August Sales Fell 6.9%: What CREA's Numbers Actually Reveal About Buyer Hesitation
Canada's Resource Advantage: What Global Investors Are Betting On in 2026