Wealthsimple Launches Prediction Markets in Canada Amid Regulatory Uncertainty
Wealthsimple shut down its Predict product in June 2026 after holding it for less than a year. The platform let users bet on sports outcomes and celebrity headlines using real money. Provincial securities regulators decided those contracts looked too much like derivatives, and derivatives require registration that Wealthsimple did not have. No regulator announced the decision or explained the reasoning to the public. Most of the debate is ahead.
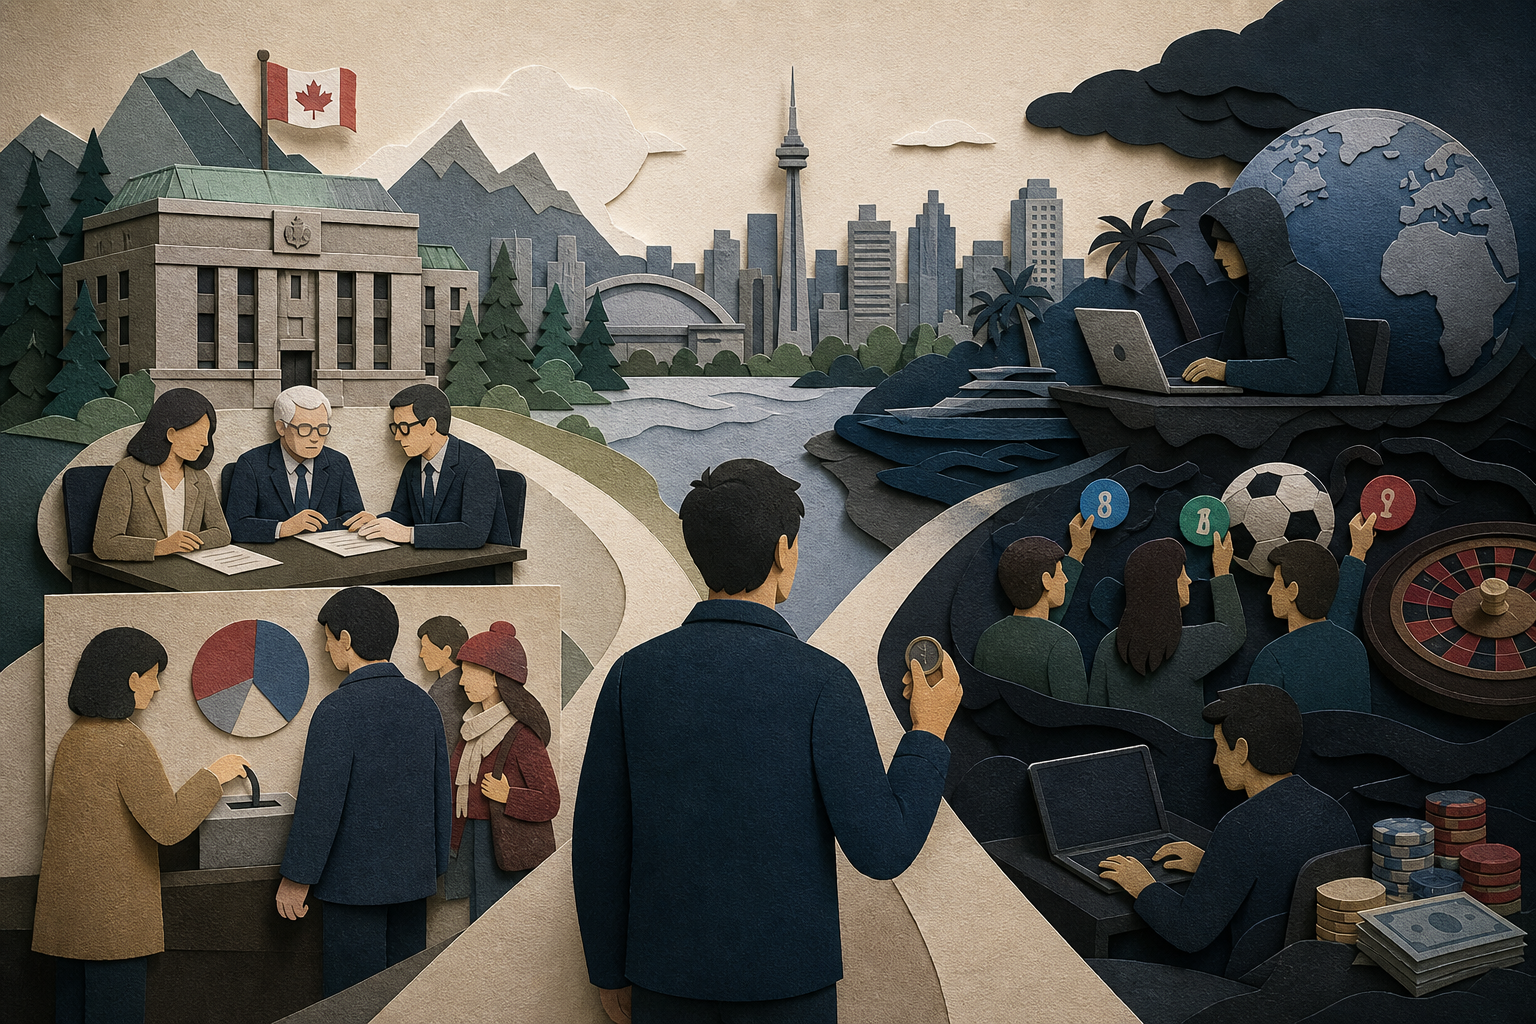
The problem isn't whether Canadians want these markets. Offshore platforms report steady traffic from Canadian IP addresses. The problem is that no Canadian regulator wants to own the file. Securities commissions say event contracts are derivatives. Gaming authorities say their mandate covers sports betting at licensed sportsbooks, not general-purpose forecasting platforms. The federal government stays out because gambling law sits with the provinces under the Constitution. So the default position is prohibition by regulatory confusion.
Two Paths, Same Dead End
Path A: treat prediction markets as securities products. Under this model, the Ontario Securities Commission and its counterparts across the 13 CSA member jurisdictions would apply the same registration and disclosure requirements they use for options or futures. An operator would need dealer registration, capital reserves, compliance staff, and a prospectus for each contract type. The cost to launch would run into seven figures before the first user signs up.
Path B: treat them as gaming products, regulated by provincial gaming authorities like iGaming Ontario. This is the model for sports betting, which became legal in Ontario in 2022. The issue is scope. Gaming regulators have clear authority over sporting events and casino-style games. Their mandate does not obviously extend to contracts on central bank rate decisions, election outcomes, or whether a tech company hits its earnings target. Expanding that mandate would require legislative changes in every province. None have proposed it.
Both paths assume the contracts are primarily recreational. Neither accounts for the informational function prediction markets are designed to serve. A market pricing the probability of a Bank of Canada rate cut in September is not a game. It aggregates dispersed information from thousands of participants with actual money at stake. That output is more reliable than most polling, which suffers from social desirability bias and costs respondents nothing to answer dishonestly.
Why the U.S. Ruling Changed Nothing Here
Kalshi's win against the CFTC in 2024 allowed U.S. political prediction markets to operate under federal oversight. Canada watched. Nothing moved. The U.S. has a single federal commodities regulator. Canada has 13 provincial and territorial securities commissions and 13 provincial and territorial gaming authorities, none of which want to be the first to permit contracts the others might ban. The constitutional split between federal criminal law and provincial civil law makes coordinated action nearly impossible. A product legal in Ontario faces provincial jurisdiction boundaries that shift at the Quebec border, creating ambiguity that discourages operators.
The real cost is the shadow market. Polymarket, based offshore, does not verify Canadian users. It does not enforce anti-money laundering rules. It does not guarantee payout. When disputes happen, there is no regulator to call. Canadians are trading there anyway, using VPNs and stablecoins, because Canada offers no legal alternative.
What Breaks the Stalemate
A workable model exists. Carve out a third category under provincial law: information markets, distinct from both securities and gaming. Require registration and consumer protection rules but skip the prospectus-per-contract burden that makes Path A unworkable. Limit contract types to verifiable public events with objective outcomes, excluding insider-prone corporate decisions. Require operators to publish aggregated probability data as a public good, the way exchanges publish order book data.
Alberta or Ontario could do this unilaterally. The first province to offer a clear path captures the operators, the tax revenue, and the right to publish the data everyone watches. The rest either follow or watch their residents trade offshore. Regulatory silence dressed up as caution lets the market move to other jurisdictions and offshore platforms.



Wealthsimple shut down its Predict product in June 2026 after holding it for less than a year. The platform let users bet on sports outcomes and celebrity headlines using real money. Provincial securities regulators decided those contracts looked too much like derivatives, and derivatives require registration that Wealthsimple did not have. No regulator announced the decision or explained the reasoning to the public. Most of the debate is ahead.
The problem isn't whether Canadians want these markets. Offshore platforms report steady traffic from Canadian IP addresses. The problem is that no Canadian regulator wants to own the file. Securities commissions say event contracts are derivatives. Gaming authorities say their mandate covers sports betting at licensed sportsbooks, not general-purpose forecasting platforms. The federal government stays out because gambling law sits with the provinces under the Constitution. So the default position is prohibition by regulatory confusion.
Two Paths, Same Dead End
Path A: treat prediction markets as securities products. Under this model, the Ontario Securities Commission and its counterparts across the 13 CSA member jurisdictions would apply the same registration and disclosure requirements they use for options or futures. An operator would need dealer registration, capital reserves, compliance staff, and a prospectus for each contract type. The cost to launch would run into seven figures before the first user signs up.
Path B: treat them as gaming products, regulated by provincial gaming authorities like iGaming Ontario. This is the model for sports betting, which became legal in Ontario in 2022. The issue is scope. Gaming regulators have clear authority over sporting events and casino-style games. Their mandate does not obviously extend to contracts on central bank rate decisions, election outcomes, or whether a tech company hits its earnings target. Expanding that mandate would require legislative changes in every province. None have proposed it.
Both paths assume the contracts are primarily recreational. Neither accounts for the informational function prediction markets are designed to serve. A market pricing the probability of a Bank of Canada rate cut in September is not a game. It aggregates dispersed information from thousands of participants with actual money at stake. That output is more reliable than most polling, which suffers from social desirability bias and costs respondents nothing to answer dishonestly.
Why the U.S. Ruling Changed Nothing Here
Kalshi's win against the CFTC in 2024 allowed U.S. political prediction markets to operate under federal oversight. Canada watched. Nothing moved. The U.S. has a single federal commodities regulator. Canada has 13 provincial and territorial securities commissions and 13 provincial and territorial gaming authorities, none of which want to be the first to permit contracts the others might ban. The constitutional split between federal criminal law and provincial civil law makes coordinated action nearly impossible. A product legal in Ontario faces provincial jurisdiction boundaries that shift at the Quebec border, creating ambiguity that discourages operators.
The real cost is the shadow market. Polymarket, based offshore, does not verify Canadian users. It does not enforce anti-money laundering rules. It does not guarantee payout. When disputes happen, there is no regulator to call. Canadians are trading there anyway, using VPNs and stablecoins, because Canada offers no legal alternative.
What Breaks the Stalemate
A workable model exists. Carve out a third category under provincial law: information markets, distinct from both securities and gaming. Require registration and consumer protection rules but skip the prospectus-per-contract burden that makes Path A unworkable. Limit contract types to verifiable public events with objective outcomes, excluding insider-prone corporate decisions. Require operators to publish aggregated probability data as a public good, the way exchanges publish order book data.
Alberta or Ontario could do this unilaterally. The first province to offer a clear path captures the operators, the tax revenue, and the right to publish the data everyone watches. The rest either follow or watch their residents trade offshore. Regulatory silence dressed up as caution lets the market move to other jurisdictions and offshore platforms.
Sources
Read Next
GIC rates stall as bonds retreat: why deposit accounts still lag
Why Your Employer's Life Insurance Probably Covers Less Than You Think
August Sales Fell 6.9%: What CREA's Numbers Actually Reveal About Buyer Hesitation
Canada's Resource Advantage: What Global Investors Are Betting On in 2026