Fortress to Private Credit Lenders: AI Infrastructure Demands Discipline, Not FOMO
A $7 billion loan backed by Nvidia H100 chips looked bulletproof in early 2025. By mid-2026, the B200 architecture had cut the resale value of that collateral by half. The lender, a mid-tier private credit fund chasing yield in GPU servers and data centers, found itself holding what amounted to a warehouse full of outdated hardware on a seven-year repayment schedule.
Fortress Investment Group has spent the past quarter telling private credit managers that this scenario is not hypothetical. The surge in demand for data centers, specialized GPUs, and power transmission equipment has drawn billions from non-bank lenders competing for deals that didn't exist three years ago. The problem is structural: AI hardware depreciates faster than the loan terms anticipate, and the secondary market for obsolete chips is shallow at best.
The Asset-Liability Gap Nobody Underwrites
Private credit has historically financed predictable assets. Real estate holds value. Machinery wears down on known schedules. GPU servers and data centers break both patterns. A high-end GPU might have a replacement cycle of three to five years, but the loan runs seven to ten. If the borrower defaults in year four, the collateral may be worth a fraction of the outstanding balance.
The energy contract matters more than the servers. A data center without a long-term power agreement is worth roughly what the building would fetch as warehouse space. Lenders who focus on the GPU count while ignoring the utility hookup are underwriting the wrong asset. Fortress points to concentration risk as the deeper issue: if Microsoft, Google, and Amazon stop leasing from the startups being financed, the entire tenant base disappears at once.
Why This Isn't Just Tech Lending
For a decade, private credit in technology meant lending against software subscription revenue. That model was asset-light, predictable, and built on recurring cash flow. The AI boom forced a pivot back to asset-heavy lending, and many credit analysts who cut their teeth on SaaS have little experience managing physical depreciation.
The shift shows in deal structure. Recent transactions have topped $5 billion for single-tranche GPU cloud buildouts, with interest rates significantly above investment-grade corporate debt despite the ostensibly "hard" collateral. What looks like a steel-and-concrete play is actually a bet on the pace of architectural obsolescence. If the next generation of chips arrives faster than the model predicted, the hard asset becomes a liability.
Fortress's warning centers on residual value assumptions. A server farm financed today cannot be assumed to hold any meaningful worth in 2030. If the collateral drops to near-zero, the loan is effectively unsecured from day one. That changes the risk profile entirely, but the pricing often doesn't reflect it.
The Power Arbitrage Cuts Both Ways
Data center power demand is projected to double by 2030, according to the International Energy Agency. That creates scarcity, and scarcity can protect lenders. A facility with a locked-in grid connection has a moat that software never did.
But scarcity also means construction delays, permitting bottlenecks, and capital expenditure overruns. A developer who promised a 2027 online date but can't secure transformer capacity until 2028 has burned through twelve months of interest expense with no revenue. The power bottleneck is both the asset and the risk.
Private credit players, Blackstone, Blue Owl, Apollo, are competing for market share in what amounts to the largest data center and GPU buildout in a generation. The firms with deep real estate and energy teams arguably understand these risks better than traditional banks. The ones chasing yield without that expertise are the ones Fortress is addressing.
The discipline Fortress calls for isn't about avoiding AI entirely. Sitting out the sector means irrelevance. The discipline is in underwriting the utility agreement, the depreciation curve, and the tenant concentration before underwriting the chip count. Treating GPU servers and data centers as specialized real estate with a high failure rate, rather than as a tech investment with hard collateral, changes which deals make sense and which do not.


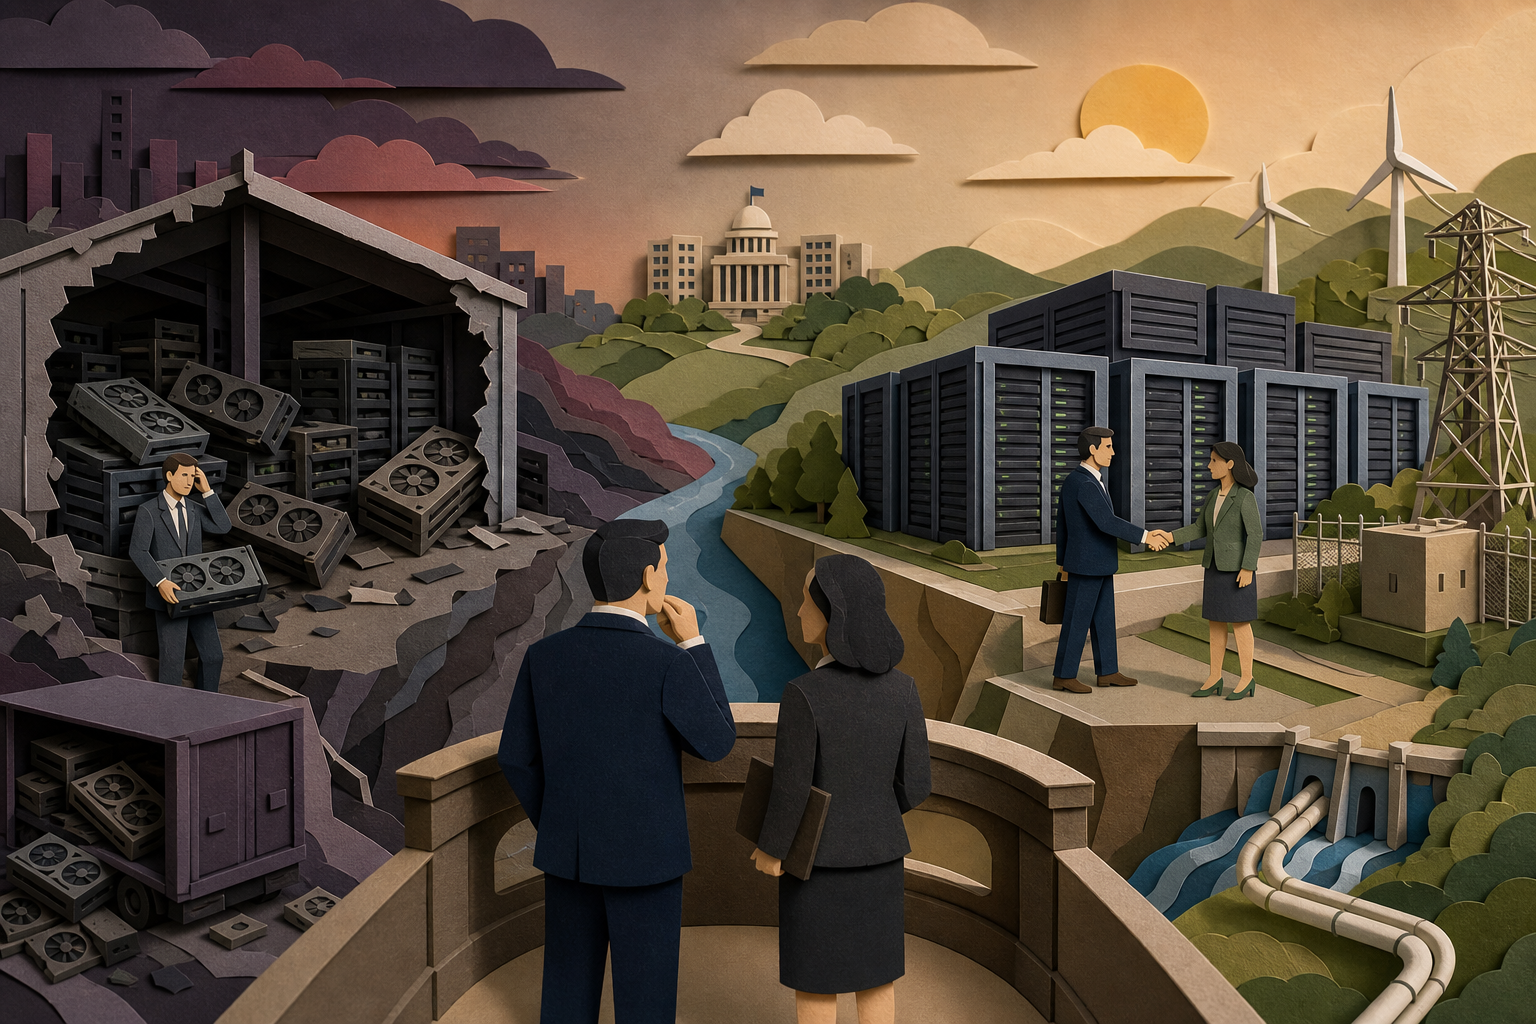

A $7 billion loan backed by Nvidia H100 chips looked bulletproof in early 2025. By mid-2026, the B200 architecture had cut the resale value of that collateral by half. The lender, a mid-tier private credit fund chasing yield in GPU servers and data centers, found itself holding what amounted to a warehouse full of outdated hardware on a seven-year repayment schedule.
Fortress Investment Group has spent the past quarter telling private credit managers that this scenario is not hypothetical. The surge in demand for data centers, specialized GPUs, and power transmission equipment has drawn billions from non-bank lenders competing for deals that didn't exist three years ago. The problem is structural: AI hardware depreciates faster than the loan terms anticipate, and the secondary market for obsolete chips is shallow at best.
The Asset-Liability Gap Nobody Underwrites
Private credit has historically financed predictable assets. Real estate holds value. Machinery wears down on known schedules. GPU servers and data centers break both patterns. A high-end GPU might have a replacement cycle of three to five years, but the loan runs seven to ten. If the borrower defaults in year four, the collateral may be worth a fraction of the outstanding balance.
The energy contract matters more than the servers. A data center without a long-term power agreement is worth roughly what the building would fetch as warehouse space. Lenders who focus on the GPU count while ignoring the utility hookup are underwriting the wrong asset. Fortress points to concentration risk as the deeper issue: if Microsoft, Google, and Amazon stop leasing from the startups being financed, the entire tenant base disappears at once.
Why This Isn't Just Tech Lending
For a decade, private credit in technology meant lending against software subscription revenue. That model was asset-light, predictable, and built on recurring cash flow. The AI boom forced a pivot back to asset-heavy lending, and many credit analysts who cut their teeth on SaaS have little experience managing physical depreciation.
The shift shows in deal structure. Recent transactions have topped $5 billion for single-tranche GPU cloud buildouts, with interest rates significantly above investment-grade corporate debt despite the ostensibly "hard" collateral. What looks like a steel-and-concrete play is actually a bet on the pace of architectural obsolescence. If the next generation of chips arrives faster than the model predicted, the hard asset becomes a liability.
Fortress's warning centers on residual value assumptions. A server farm financed today cannot be assumed to hold any meaningful worth in 2030. If the collateral drops to near-zero, the loan is effectively unsecured from day one. That changes the risk profile entirely, but the pricing often doesn't reflect it.
The Power Arbitrage Cuts Both Ways
Data center power demand is projected to double by 2030, according to the International Energy Agency. That creates scarcity, and scarcity can protect lenders. A facility with a locked-in grid connection has a moat that software never did.
But scarcity also means construction delays, permitting bottlenecks, and capital expenditure overruns. A developer who promised a 2027 online date but can't secure transformer capacity until 2028 has burned through twelve months of interest expense with no revenue. The power bottleneck is both the asset and the risk.
Private credit players, Blackstone, Blue Owl, Apollo, are competing for market share in what amounts to the largest data center and GPU buildout in a generation. The firms with deep real estate and energy teams arguably understand these risks better than traditional banks. The ones chasing yield without that expertise are the ones Fortress is addressing.
The discipline Fortress calls for isn't about avoiding AI entirely. Sitting out the sector means irrelevance. The discipline is in underwriting the utility agreement, the depreciation curve, and the tenant concentration before underwriting the chip count. Treating GPU servers and data centers as specialized real estate with a high failure rate, rather than as a tech investment with hard collateral, changes which deals make sense and which do not.
Read Next
Birch Hill builds a regional aviation network in British Columbia through Harbour Air's Pacific Coastal acquisition
South Korea's Stock Market Has Become a National Liability
Tech CEOs Walk the Investor Tightrope: Signal AI Risk Without Cutting Off Billions in Funding
Canada Child Benefit Payments Arrive Early This September, Here's What Changed in July