AI Mortgage Approvals Promise Speed and Savings, But Nobody's Explaining the Privacy Cost
A borrower uploads three months of bank statements at 11 PM on a Tuesday. By 11:07, the algorithm has pulled her credit file, cross-referenced her income against CRA records, verified her employment through open banking credentials, and issued a conditional approval. No phone calls. No faxed pay stubs. No waiting for a human to return from lunch.
That's the promise Canadian lenders are selling as AI moves from pilot programs to production. The pitch is seductive: mortgage origination that traditionally took 30 to 45 days could compress into as little as two weeks with AI assistance, or in some cases same-day approval. Administrative savings, somewhere between 10% and 20% of origination cost, depending on whose estimate you trust, could translate into slightly lower fees or fractionally better rates. For a buyer trying to close before a seller's deadline, speed alone might be worth the switch.
What nobody's saying out loud is what you're trading to get there.
The Data Handoff Most Borrowers Won't Notice
Traditional mortgage underwriting is invasive but bounded. You give the lender specific documents. They verify what's on those documents. The information flow is one-way and constrained.
AI-driven approvals require a different bargain. To verify income in real time, the system needs read access to your bank accounts through open banking APIs. To assess spending patterns and predict default risk, it needs transaction histories, not summaries. To confirm stable employment for gig workers or contractors, people the old system often rejected, it needs utility payment data, rent history, even subscription patterns that suggest financial stability.
That's not a deeper look at the same data. That's a fundamentally wider data grant. The algorithm doesn't just check that your last three pay stubs match your application. It ingests enough of your financial life to model your behaviour and assign you a score.
By the time a human underwriter sees your file, the AI has already absorbed far more about you than the old process ever touched. It has pulled your transaction history, merchant spending patterns, utility records, rent payments, and subscription data. The human review, where it occurs, happens after the algorithm has already mapped your financial behaviour.
The Explainability Gap Nobody's Solved
Canadian lending law requires lenders to explain why they denied you. That's straightforward when a human underwriter says "your debt-to-income ratio is too high." It gets murky when an AI model says "your risk score is 652 and our threshold is 680."
The model might be flagging patterns invisible to humans, seasonal income dips, spending velocity changes, even correlations between certain merchant categories and default rates. Those patterns might be predictive. They might also be proxies for things lenders aren't legally allowed to consider.
Consumer advocacy groups have raised the bias concern: if the training data reflects decades of lending decisions that disadvantaged new immigrants or non-salaried workers, the AI inherits that bias and scales it. Lenders insist they're monitoring for this. But "monitoring" and "solving" are not the same word, and the technical fix, making the model explainable without crippling its predictive power, remains unsolved at scale.
What You're Actually Optimizing For
The efficiency pitch assumes your goal is approval speed. For plenty of buyers, it is. But speed optimizes for convenience, not cost. A same-day approval might discourage rate shopping. If the first lender in the door can close you in 48 hours, the pressure to compare five offers drops. That's good for the lender's conversion rate. It's less obviously good for you.
The 10%-to-20% cost reduction figure is real, but it's an administrative saving for the lender, not a contractual rate cut for the borrower. Whether that saving reaches you depends on competitive pressure, and an industry moving toward algorithmic pricing has less room for the kind of negotiation that used to happen when a branch manager had discretion.
Here's what's true: AI will make mortgages faster. It will lower lender costs. It might marginally reduce your rate. What it will certainly do is require you to hand over more of your financial identity than any mortgage in Canadian history has asked for. The speed is real. So is the bill.


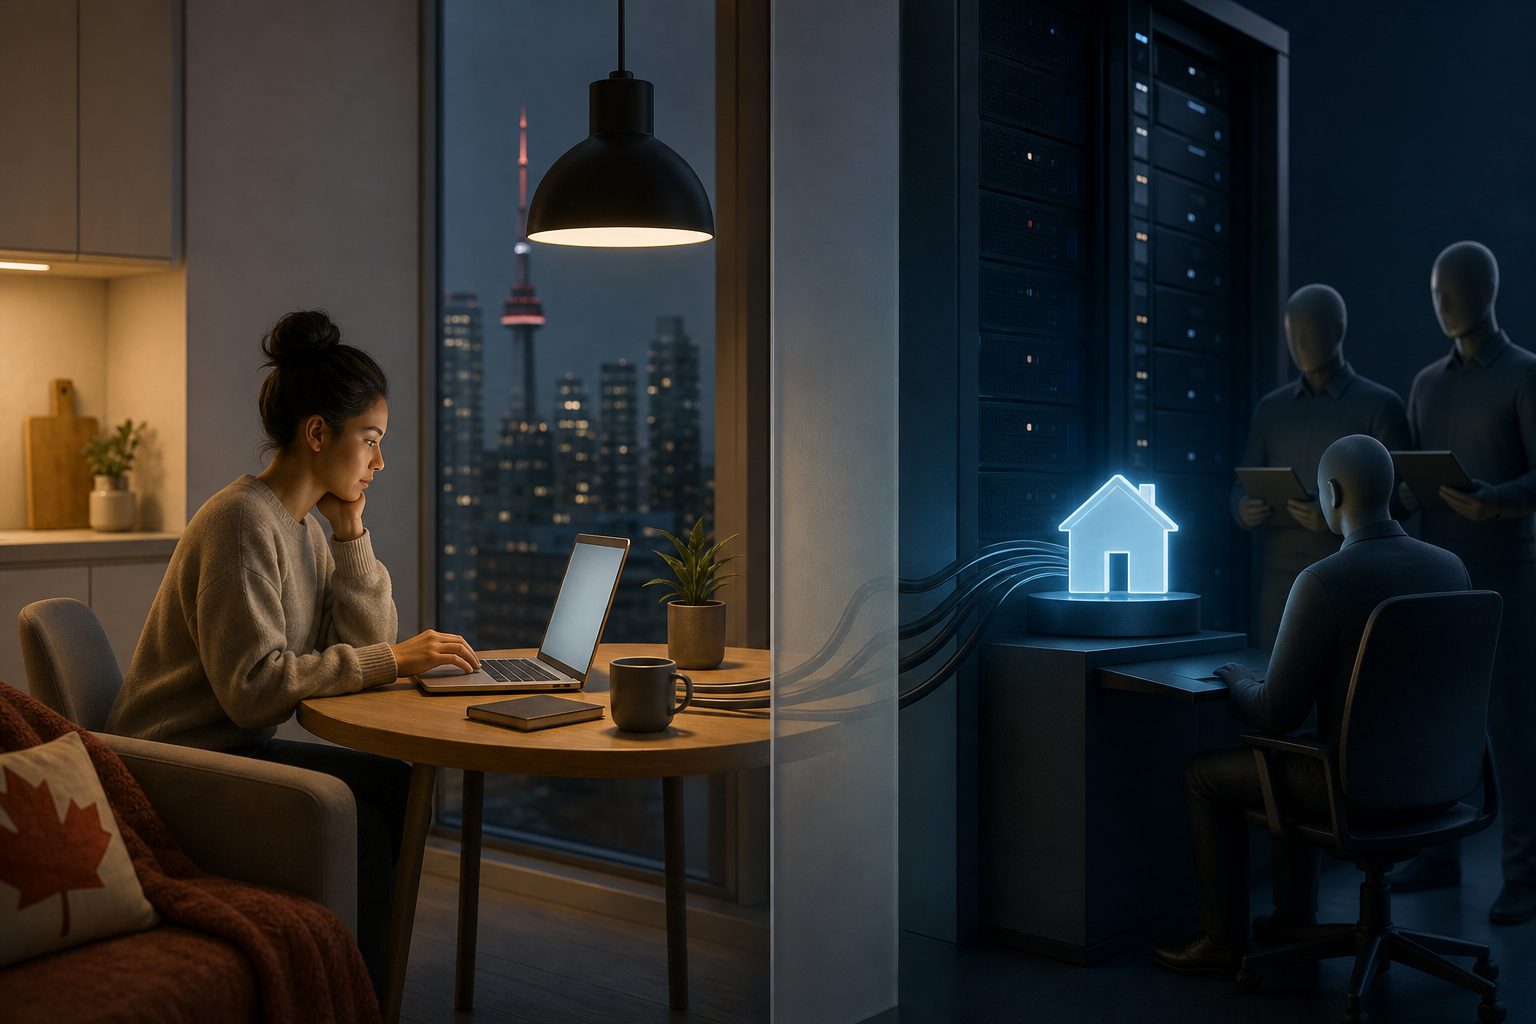

A borrower uploads three months of bank statements at 11 PM on a Tuesday. By 11:07, the algorithm has pulled her credit file, cross-referenced her income against CRA records, verified her employment through open banking credentials, and issued a conditional approval. No phone calls. No faxed pay stubs. No waiting for a human to return from lunch.
That's the promise Canadian lenders are selling as AI moves from pilot programs to production. The pitch is seductive: mortgage origination that traditionally took 30 to 45 days could compress into as little as two weeks with AI assistance, or in some cases same-day approval. Administrative savings, somewhere between 10% and 20% of origination cost, depending on whose estimate you trust, could translate into slightly lower fees or fractionally better rates. For a buyer trying to close before a seller's deadline, speed alone might be worth the switch.
What nobody's saying out loud is what you're trading to get there.
The Data Handoff Most Borrowers Won't Notice
Traditional mortgage underwriting is invasive but bounded. You give the lender specific documents. They verify what's on those documents. The information flow is one-way and constrained.
AI-driven approvals require a different bargain. To verify income in real time, the system needs read access to your bank accounts through open banking APIs. To assess spending patterns and predict default risk, it needs transaction histories, not summaries. To confirm stable employment for gig workers or contractors, people the old system often rejected, it needs utility payment data, rent history, even subscription patterns that suggest financial stability.
That's not a deeper look at the same data. That's a fundamentally wider data grant. The algorithm doesn't just check that your last three pay stubs match your application. It ingests enough of your financial life to model your behaviour and assign you a score.
By the time a human underwriter sees your file, the AI has already absorbed far more about you than the old process ever touched. It has pulled your transaction history, merchant spending patterns, utility records, rent payments, and subscription data. The human review, where it occurs, happens after the algorithm has already mapped your financial behaviour.
The Explainability Gap Nobody's Solved
Canadian lending law requires lenders to explain why they denied you. That's straightforward when a human underwriter says "your debt-to-income ratio is too high." It gets murky when an AI model says "your risk score is 652 and our threshold is 680."
The model might be flagging patterns invisible to humans, seasonal income dips, spending velocity changes, even correlations between certain merchant categories and default rates. Those patterns might be predictive. They might also be proxies for things lenders aren't legally allowed to consider.
Consumer advocacy groups have raised the bias concern: if the training data reflects decades of lending decisions that disadvantaged new immigrants or non-salaried workers, the AI inherits that bias and scales it. Lenders insist they're monitoring for this. But "monitoring" and "solving" are not the same word, and the technical fix, making the model explainable without crippling its predictive power, remains unsolved at scale.
What You're Actually Optimizing For
The efficiency pitch assumes your goal is approval speed. For plenty of buyers, it is. But speed optimizes for convenience, not cost. A same-day approval might discourage rate shopping. If the first lender in the door can close you in 48 hours, the pressure to compare five offers drops. That's good for the lender's conversion rate. It's less obviously good for you.
The 10%-to-20% cost reduction figure is real, but it's an administrative saving for the lender, not a contractual rate cut for the borrower. Whether that saving reaches you depends on competitive pressure, and an industry moving toward algorithmic pricing has less room for the kind of negotiation that used to happen when a branch manager had discretion.
Here's what's true: AI will make mortgages faster. It will lower lender costs. It might marginally reduce your rate. What it will certainly do is require you to hand over more of your financial identity than any mortgage in Canadian history has asked for. The speed is real. So is the bill.
Sources
Read Next
GIC rates stall as bonds retreat: why deposit accounts still lag
Why Your Employer's Life Insurance Probably Covers Less Than You Think
August Sales Fell 6.9%: What CREA's Numbers Actually Reveal About Buyer Hesitation
Canada's Resource Advantage: What Global Investors Are Betting On in 2026