Poilievre's Housing Plan Assumes Municipalities Will Comply. They Won't.
Poilievre's Housing Plan Assumes Municipalities Will Comply. They Won't.
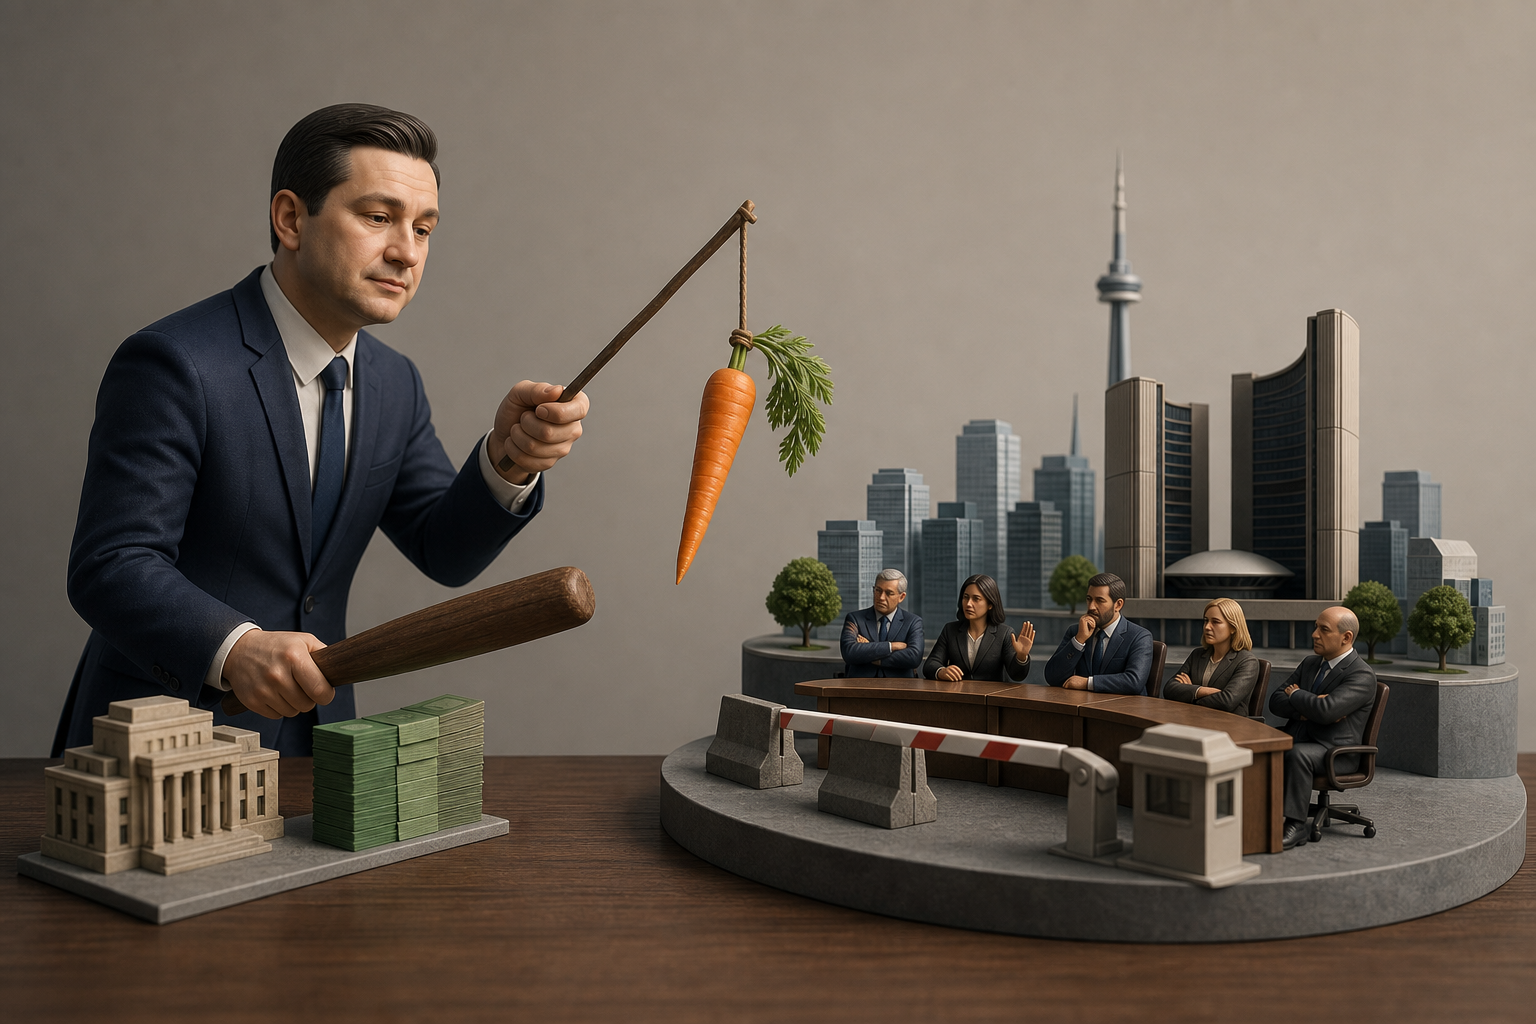
Ron Butler asked Conservative leader Pierre Poilievre how he planned to force Toronto to approve thirty thousand units next year when the city permitted eleven thousand last year and has already rejected four shovel-ready proposals this quarter. Poilievre's answer: withhold federal transfer payments for roads, transit, and water systems until they hit a 15% annual increase. That's the entire enforcement mechanism.
It won't work. Not because the policy is wrong about supply, Canada needs millions of additional units by 2030 according to CMHC's latest projections, and municipal sluggishness is a genuine bottleneck. It won't work because a federal funding penalty doesn't override the thirty-seven different ways a city council can say no without technically saying no.
The gatekeeper problem is real, the lever is imaginary
Development charges in the Greater Toronto Area run 20, 30% of a new home's final price. Poilievre estimates the federal government could eliminate roughly $7,000 to $10,000 per unit in permitting friction. The Conservative platform proposes a $100 million "Building Bonus" fund for municipalities that exceed housing targets, and threatens to cut transfer payments for roads, transit, and water systems to cities that miss the 15% benchmark.
Municipalities care more about the residents who will vote them out for approving the mid-rise next to the park than they do about federal dollars. Vancouver has turned down projects that met every zoning requirement because neighbours filed traffic complaints. Toronto planning staff recommended approval on a 1,200-unit proposal in Etobicoke in March 2026; city council voted it down 18-7 after a four-hour deputations session. No federal penalty changes that vote.
A mayor loses federal funding and blames Ottawa. A mayor approves a tower the neighbourhood hates and loses the next election. The political math is simple.
The GST cut doesn't reach the buyer
Poilievre also proposes eliminating GST on new home construction under a specific price threshold, currently floated at $800,000 in some regions. The pitch is that removing the tax will spur supply and lower buyer costs. The second half is the problem.
Developers will pocket the GST savings the same way they pocketed every other cost reduction over the last fifteen years while prices climbed. Material costs are up. Labour is scarce. A builder who saves five percent on tax and faces an eight percent increase in lumber doesn't drop the price. They hold it flat and improve margin. There is no mechanism in the proposal that turns a tax cut into a price cut for the buyer. The tax is paid by the builder. The builder is not required to pass it on. They won't.
The GST removal is real stimulus for developers. For first-time buyers it's a press release.
Conversion costs eat the land savings
The plan includes selling 15% of underutilized federal buildings for residential conversion, targeting the "missing middle", the three-to-six-storey buildings that used to fill in between single-family homes and high-rises. Converting a 1980s office building into livable apartments costs more per square foot than tearing it down and starting over.
Office buildings have different floor plates, different mechanical systems, different plumbing cores. Retrofitting an office tower for residential use requires gutting everything behind the curtain wall. Developers will buy the federal land, demolish the structure, and build new. That's fine. It adds units. But the policy is being sold as "conversion," and most of these buildings won't convert, they'll be knocked down. The land value matters. The structure is a sunk cost.
The interest rate still decides everything
Poilievre's pitch assumes supply is the binding constraint on affordability in 2026. It is, long term. But the Bank of Canada's overnight rate sits at 4.1% as of late 2025. A three-year fixed insured mortgage is currently 3.89% according to WOWA.ca. Mortgage delinquency has climbed to 0.22-0.24% as of early 2026, up from historic lows but still contained.
Those numbers move faster than housing starts. If the Bank cuts rates by 150 basis points over the next eighteen months, monthly carrying costs drop by hundreds of dollars before a single additional unit clears permitting. If rates stay elevated, a building boom still leaves first-time buyers unable to qualify under the OSFI stress test, which adds 200 basis points to the contract rate or floors at 5.25%, whichever is higher.
Supply fixes long-run affordability. Rates fix next year's payment. Poilievre is solving the right problem on the wrong timeline, and interest rate movements decide the outcome before new units matter.



Poilievre's Housing Plan Assumes Municipalities Will Comply. They Won't.
Ron Butler asked Conservative leader Pierre Poilievre how he planned to force Toronto to approve thirty thousand units next year when the city permitted eleven thousand last year and has already rejected four shovel-ready proposals this quarter. Poilievre's answer: withhold federal transfer payments for roads, transit, and water systems until they hit a 15% annual increase. That's the entire enforcement mechanism.
It won't work. Not because the policy is wrong about supply, Canada needs millions of additional units by 2030 according to CMHC's latest projections, and municipal sluggishness is a genuine bottleneck. It won't work because a federal funding penalty doesn't override the thirty-seven different ways a city council can say no without technically saying no.
The gatekeeper problem is real, the lever is imaginary
Development charges in the Greater Toronto Area run 20, 30% of a new home's final price. Poilievre estimates the federal government could eliminate roughly $7,000 to $10,000 per unit in permitting friction. The Conservative platform proposes a $100 million "Building Bonus" fund for municipalities that exceed housing targets, and threatens to cut transfer payments for roads, transit, and water systems to cities that miss the 15% benchmark.
Municipalities care more about the residents who will vote them out for approving the mid-rise next to the park than they do about federal dollars. Vancouver has turned down projects that met every zoning requirement because neighbours filed traffic complaints. Toronto planning staff recommended approval on a 1,200-unit proposal in Etobicoke in March 2026; city council voted it down 18-7 after a four-hour deputations session. No federal penalty changes that vote.
A mayor loses federal funding and blames Ottawa. A mayor approves a tower the neighbourhood hates and loses the next election. The political math is simple.
The GST cut doesn't reach the buyer
Poilievre also proposes eliminating GST on new home construction under a specific price threshold, currently floated at $800,000 in some regions. The pitch is that removing the tax will spur supply and lower buyer costs. The second half is the problem.
Developers will pocket the GST savings the same way they pocketed every other cost reduction over the last fifteen years while prices climbed. Material costs are up. Labour is scarce. A builder who saves five percent on tax and faces an eight percent increase in lumber doesn't drop the price. They hold it flat and improve margin. There is no mechanism in the proposal that turns a tax cut into a price cut for the buyer. The tax is paid by the builder. The builder is not required to pass it on. They won't.
The GST removal is real stimulus for developers. For first-time buyers it's a press release.
Conversion costs eat the land savings
The plan includes selling 15% of underutilized federal buildings for residential conversion, targeting the "missing middle", the three-to-six-storey buildings that used to fill in between single-family homes and high-rises. Converting a 1980s office building into livable apartments costs more per square foot than tearing it down and starting over.
Office buildings have different floor plates, different mechanical systems, different plumbing cores. Retrofitting an office tower for residential use requires gutting everything behind the curtain wall. Developers will buy the federal land, demolish the structure, and build new. That's fine. It adds units. But the policy is being sold as "conversion," and most of these buildings won't convert, they'll be knocked down. The land value matters. The structure is a sunk cost.
The interest rate still decides everything
Poilievre's pitch assumes supply is the binding constraint on affordability in 2026. It is, long term. But the Bank of Canada's overnight rate sits at 4.1% as of late 2025. A three-year fixed insured mortgage is currently 3.89% according to WOWA.ca. Mortgage delinquency has climbed to 0.22-0.24% as of early 2026, up from historic lows but still contained.
Those numbers move faster than housing starts. If the Bank cuts rates by 150 basis points over the next eighteen months, monthly carrying costs drop by hundreds of dollars before a single additional unit clears permitting. If rates stay elevated, a building boom still leaves first-time buyers unable to qualify under the OSFI stress test, which adds 200 basis points to the contract rate or floors at 5.25%, whichever is higher.
Supply fixes long-run affordability. Rates fix next year's payment. Poilievre is solving the right problem on the wrong timeline, and interest rate movements decide the outcome before new units matter.
Read Next
South Korea's Stock Market Has Become a National Liability
Tech CEOs Walk the Investor Tightrope: Signal AI Risk Without Cutting Off Billions in Funding
Canada Child Benefit Payments Arrive Early This September, Here's What Changed in July
How Auckland's Zoning Reform Supercharged Housing Starts in Five Years—and What Canada is Missing