Five indicators that will decide whether small caps hold their 2026 gains
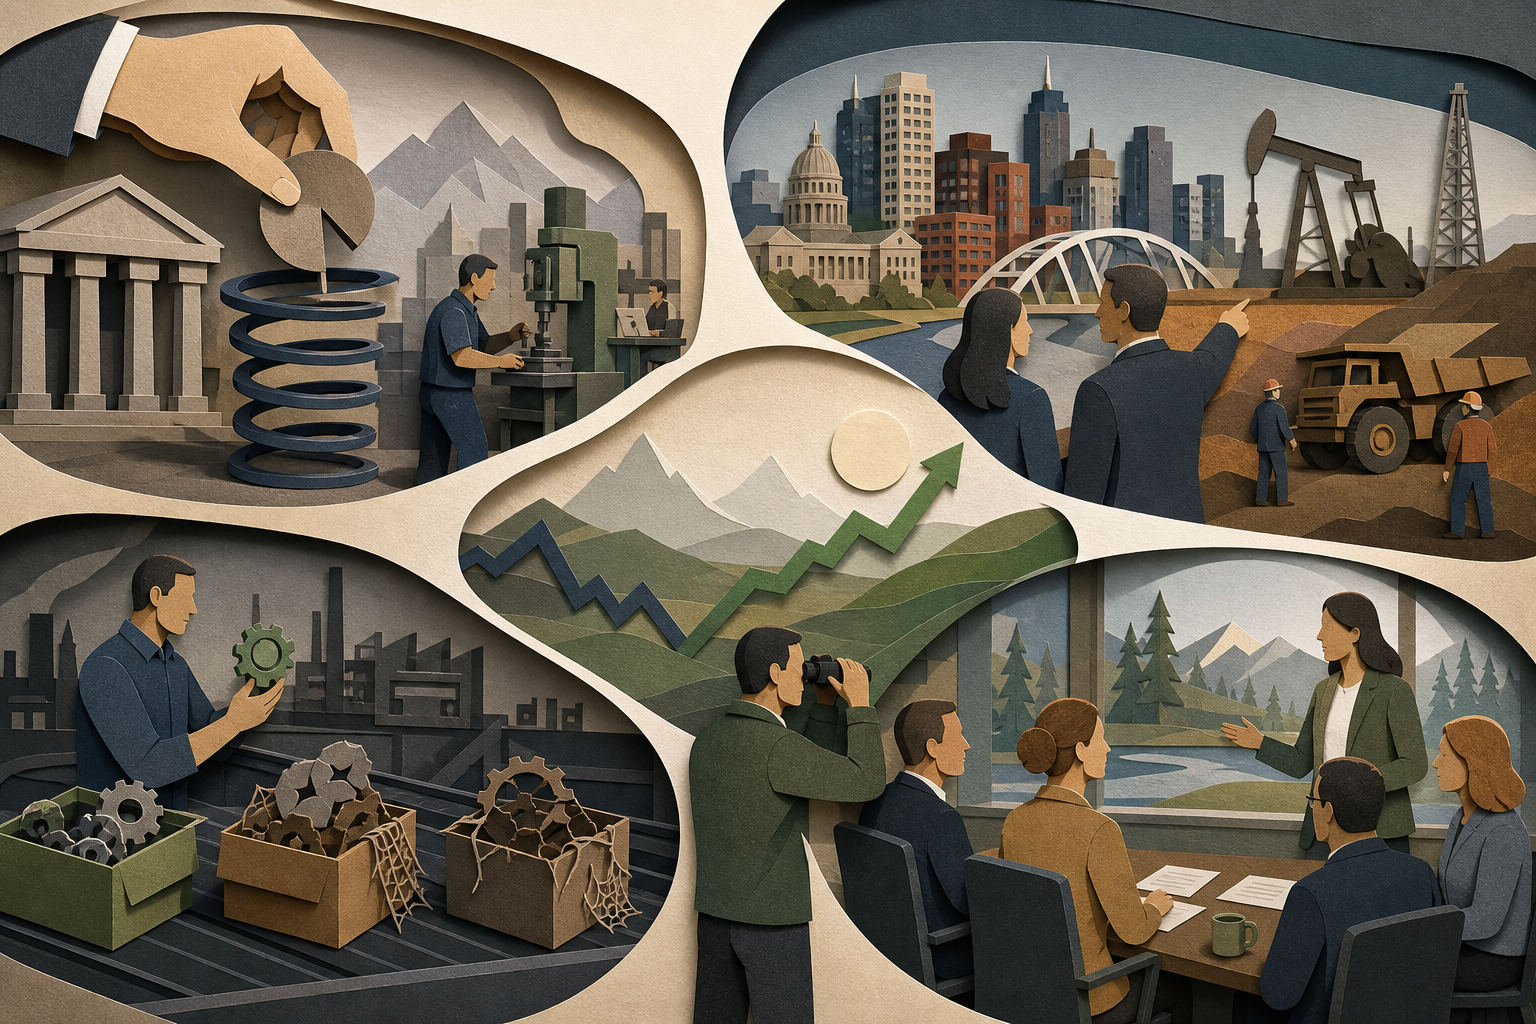
The valuation gap between Canada's smallest public companies and the TSX's blue-chip giants narrowed materially in the first eight months of 2026, reversing a two-year pattern in which only a handful of large technology firms delivered meaningful returns. Whether that convergence holds through year-end depends less on sentiment than on five structural conditions that historically separate temporary rallies from sustained recoveries.
The Bank of Canada's next three moves
Small-cap companies typically carry floating-rate debt at levels that would sink a household budget. The Bank of Canada held its policy rate at 2.25 per cent through late 2025 and into 2026. For a mid-sized Edmonton manufacturer or a junior Calgary energy service provider, borrowing costs remained above historical lows even as inflation approached the 2 per cent target. A quarter-point cut matters more to a $50-million company with $20 million in variable-rate loans than it does to a cash-heavy multinational. Markets are pricing in further stabilization, but if inflation stays above target and rate cuts stall, the small-cap rally stalls with them.
Whether profitability overtakes growth as the filter
A significant portion of the Russell 2000 and comparable Canadian small-cap indices consists of companies that are not yet cash-flow positive, what the industry calls zombies when the cash burn outlasts the runway. For years, investors tolerated that in exchange for growth narratives. That tolerance is narrowing. Institutional money is rotating toward smaller companies that already show a profit. The dividing line is whether a company's operations generate cash before external capital arrives, which means the rally's second phase will likely belong to the minority of small caps that can cover their bills.
Merger and acquisition appetite among large buyers
When small-cap valuations were trading at 12, 14 times forward earnings in early 2026 while large caps sat near 20, 22 times, the spread created a natural incentive for larger companies to acquire smaller ones at a discount. An increase in takeover activity is a reliable signal that the small-cap market has bottomed and begun recovering, because acquirers typically wait until they believe the worst of the repricing is behind them. If M&A volume rises through the fourth quarter, it confirms that sophisticated buyers see value the market has not yet fully priced in. If it stays flat, the rally may be speculative rather than structural.
TSX Venture Exchange trading volume as a leading indicator
TMX Group data shows the TSX Venture Exchange, home to junior resource companies and early-stage tech firms, saw increased trading volume in 2026, signaling renewed risk appetite among retail and institutional investors. Volume precedes price. When activity picks up in the most speculative tier of the small-cap market, it suggests capital is moving down the risk curve in search of return. When volume drops, even while prices hold, the rally is typically running on momentum rather than conviction. Watch the three-month rolling average; a sustained increase above the 2023, 2025 baseline is the kind of structural shift that supports a multi-quarter move.
The concentration risk hedge as a permanent shift or a trade
Portfolio managers rebalancing away from a handful of overvalued technology stocks in the Magnificent Seven and similar large-cap leaders need somewhere to put the capital, and small caps absorbed much of it in 2026. The durability of the rally depends on whether that rebalancing is a one-time adjustment or the start of a longer-term shift. If the mega-cap concentration unwinds further, small caps benefit structurally. If large-cap tech stabilizes and institutional allocations stop moving, the fuel behind the rally disappears even if nothing changes in the small-cap market itself.
The pattern that matters is whether these five conditions move together or separately. A rally built on one or two supports is a trade. A rally built on all five is a cycle.

The valuation gap between Canada's smallest public companies and the TSX's blue-chip giants narrowed materially in the first eight months of 2026, reversing a two-year pattern in which only a handful of large technology firms delivered meaningful returns. Whether that convergence holds through year-end depends less on sentiment than on five structural conditions that historically separate temporary rallies from sustained recoveries.
The Bank of Canada's next three moves
Small-cap companies typically carry floating-rate debt at levels that would sink a household budget. The Bank of Canada held its policy rate at 2.25 per cent through late 2025 and into 2026. For a mid-sized Edmonton manufacturer or a junior Calgary energy service provider, borrowing costs remained above historical lows even as inflation approached the 2 per cent target. A quarter-point cut matters more to a $50-million company with $20 million in variable-rate loans than it does to a cash-heavy multinational. Markets are pricing in further stabilization, but if inflation stays above target and rate cuts stall, the small-cap rally stalls with them.
Whether profitability overtakes growth as the filter
A significant portion of the Russell 2000 and comparable Canadian small-cap indices consists of companies that are not yet cash-flow positive, what the industry calls zombies when the cash burn outlasts the runway. For years, investors tolerated that in exchange for growth narratives. That tolerance is narrowing. Institutional money is rotating toward smaller companies that already show a profit. The dividing line is whether a company's operations generate cash before external capital arrives, which means the rally's second phase will likely belong to the minority of small caps that can cover their bills.
Merger and acquisition appetite among large buyers
When small-cap valuations were trading at 12, 14 times forward earnings in early 2026 while large caps sat near 20, 22 times, the spread created a natural incentive for larger companies to acquire smaller ones at a discount. An increase in takeover activity is a reliable signal that the small-cap market has bottomed and begun recovering, because acquirers typically wait until they believe the worst of the repricing is behind them. If M&A volume rises through the fourth quarter, it confirms that sophisticated buyers see value the market has not yet fully priced in. If it stays flat, the rally may be speculative rather than structural.
TSX Venture Exchange trading volume as a leading indicator
TMX Group data shows the TSX Venture Exchange, home to junior resource companies and early-stage tech firms, saw increased trading volume in 2026, signaling renewed risk appetite among retail and institutional investors. Volume precedes price. When activity picks up in the most speculative tier of the small-cap market, it suggests capital is moving down the risk curve in search of return. When volume drops, even while prices hold, the rally is typically running on momentum rather than conviction. Watch the three-month rolling average; a sustained increase above the 2023, 2025 baseline is the kind of structural shift that supports a multi-quarter move.
The concentration risk hedge as a permanent shift or a trade
Portfolio managers rebalancing away from a handful of overvalued technology stocks in the Magnificent Seven and similar large-cap leaders need somewhere to put the capital, and small caps absorbed much of it in 2026. The durability of the rally depends on whether that rebalancing is a one-time adjustment or the start of a longer-term shift. If the mega-cap concentration unwinds further, small caps benefit structurally. If large-cap tech stabilizes and institutional allocations stop moving, the fuel behind the rally disappears even if nothing changes in the small-cap market itself.
The pattern that matters is whether these five conditions move together or separately. A rally built on one or two supports is a trade. A rally built on all five is a cycle.
Sources
Read Next
Why Federal Housing Funds Sit Unspent While Wait Lists Grow
Why Jumbo Corporate Deals Are Widening Credit Spreads Right Now
Mortgage fraud in Canada fell to 0.2%, what that tells us about underwriting and buyer behaviour
TD Bank Commits $10 Billion to Share Buyback After OSFI Lowers Capital Buffer to 3.0%